

Bond investors are facing an unusually confusing environment. Inflation remains stubbornly above the Federal Reserve’s target, geopolitical risks have pushed energy prices higher, and an unexpectedly resilient economy has complicated monetary policy expectations. Meanwhile, concerns about federal borrowing, growing Treasury supply, and shifting expectations for long-term interest rates have contributed to substantial volatility at the longer end of the bond market.
However, within this confusion, one area of the bond market could be a significant winner for portfolios.
In a market where the path for inflation, economic growth, and interest rates remains uncertain, investors don’t necessarily have to make a large bet on what comes next. Short-duration bonds could offer the best combination of high income and manageable interest-rate sensitivity that investors need right now.
The Fed Is Raising Rates Again
Stubborn — that’s the best word to describe inflation over the past year or so. After declining from post-pandemic highs, various inflation measures have plateaued, staying above central bank targets for what seems like quarters. Now those measures have started to climb again.
To that end, the Federal Reserve made it official.
For the first time in three years, policymakers raised interest rates. At its September meeting, the Federal Reserve raised the federal funds target range by 25 basis points to 3.75%–4.00%, its first increase since July 2023.
The decision was unanimous.
The Fed acknowledged that economic activity continues to expand at a solid pace, with resilient domestic spending, strong productivity growth, and robust capital investment. Policymakers remain concerned, however, about inflation, which is still running well above the central bank’s 2% target.
More importantly for investors, the September hike may not be a one-and-done move.
Federal Reserve projections showed 16 of 18 policymakers expecting at least one additional quarter-point increase before the end of 2026. The median projection puts the federal funds rate at 4.00%–4.25% at year-end and at the same level at the end of 2027.
For bond investors, the message is clear. The market spent years preparing for falling rates, but the Fed has begun tightening again, making duration management increasingly important.
Short-Term Bonds Reduce the Need to Predict What Comes Next
Higher rates are generally bad news for bonds because bond prices move inversely to yields — a relationship known as duration.
If a bond portfolio has a duration of two years, a one-percentage-point rise in interest rates would theoretically reduce its price by approximately 2%. A portfolio with a duration of eight years could fall roughly 8% from the same move, before accounting for income and other factors, meaning unexpected yield increases magnify losses as duration grows.
Today’s environment gives long-duration bonds ample reasons to remain unpredictable, including inflation, federal deficits, Treasury issuance, and shifting expectations for economic growth. Volatility has already risen at the long end of the curve this year, and the Fed’s rate hike has only added to that pressure.
The front end of the bond market is particularly useful for investors who don’t want to make a large directional bet on rates. Short-term bond portfolios generally carry durations of one to 3.5 years, while ultrashort strategies typically maintain durations below one year, making them substantially less sensitive to rate changes than intermediate- or long-term bond funds.
You can see that in this graph from J.P. Morgan.
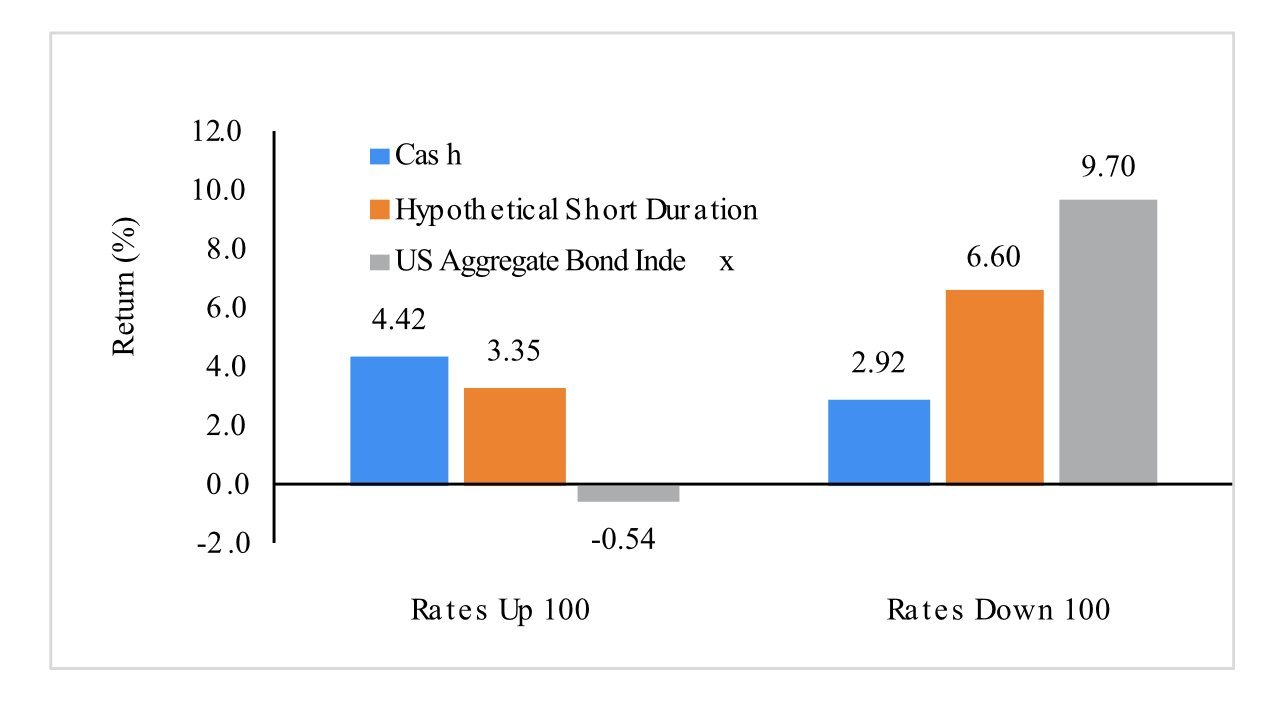
What’s particularly notable is that investors are being paid well on the shorter end of the curve. J.P. Morgan Asset Management estimates that the front end of the yield curve offers yields of roughly 4% to 5%, allowing investors to earn meaningful income without accepting the interest-rate sensitivity of intermediate- and long-term bonds.
Those high yields also provide considerable cushion before short-term bonds would experience losses. J.P. Morgan predicts that rates would have to rise by more than 2.75 percentage points before a representative short-duration strategy would generate a negative 12-month return.
Using ETFs to Invest in Short-Term Bonds
Given the rate uncertainty and the Federal Reserve’s recent moves, short-term bonds could be fixed-income’s sweet spot, offering meaningful yield alongside duration protection — exactly what investors need today.
Duration and ‘short term’ define only a timeline. Investors can choose among funds holding Treasuries, investment-grade corporate bonds, securitized debt, or diversified combinations of several fixed-income sectors.
This is why ETFs have made building a short-duration allocation considerably easier.
With one or several ETFs, investors can build a short-term portfolio matched to their credit tolerances.
Short-Term Bond ETFs
These ETFs are selected for their ability to access short-term credit-duration bonds at low cost, sorted by year-to-date (YTD) total return, which ranges from 2.6% to 4.9%. Expense ratios range from 0.03% to 0.55%, yields range from 2.4% to 4.8%, and assets under management (AUM) range from $468 million to $41 billion.
| Ticker | Name | AUM | YTD Total Ret (%) | Yield (%) | Exp Ratio | Security Type | Actively Managed? |
|---|---|---|---|---|---|---|---|
| IGSB | iShares 1-5 Year investment-grade Corporate Bond ETF | $21.7B | 4.9% | 4.4% | 0.04% | ETF | No |
| DFSD | Dimensional Short-Duration fixed-income ETF | $4.8B | 4.8% | 3.9% | 0.17% | ETF | Yes |
| SCHJ | Schwab 1-5 Year Corporate Bond ETF | $529M | 4.8% | 4.8% | 0.03% | ETF | No |
| VCSH | Vanguard Short-Term Corporate Bond ETF | $41.1B | 4.7% | 4.5% | 0.03% | ETF | No |
| FSIG | First Trust Limited Duration investment-grade Corporate ETF | $1.3B | 4.5% | 4.54% | 0.55% | ETF | Yes |
| SLQD | iShares 0-5 Year investment-grade Corporate Bond ETF | $2.3B | 4.3% | 4.2% | 0.06% | ETF | No |
| SPSB | SPDR Portfolio Short Term Corporate Bond ETF | $8.4B | 3.9% | 4.8% | 0.04% | ETF | No |
| SHM | SPDR Nuveen Bloomberg Short Term Municipal Bond ETF | $3.4B | 3.2% | 2.6% | 0.20% | ETF | No |
| CGSM | Capital Group Short Duration Municipal Income ETF | $709M | 2.9% | 3.6% | 0.25% | ETF | Yes |
| FSMB | First Trust Short Duration Managed Municipal ETF | $468M | 2.8% | 3.1% | 0.55% | ETF | Yes |
| SUB | iShares Short-Term National Muni Bond ETF | $9.9B | 2.7% | 2.4% | 0.07% | ETF | No |
| MEAR | BlackRock Short Maturity Municipal Bond ETF | $1.1B | 2.6% | 2.8% | 0.25% | ETF | Yes |
The bond market is sending investors conflicting signals.
Inflation remains elevated, the economy continues to grow, and the Fed has resumed raising rates. Long-term Treasury yields remain volatile, while fiscal concerns and large borrowing needs have added further uncertainty.
Predicting exactly where interest rates will be a year from now is unusually difficult, but investors don’t necessarily have to.
Short-duration bonds now offer something largely unavailable during the low-rate era: meaningful income with relatively limited interest-rate risk. Yields of around 4% to 5% provide a substantial income cushion, while shorter maturities reduce potential damage if rates continue rising.
Bottom Line
The Fed’s return to rate hikes has created an attractive opportunity at the short end of the bond market. Short-duration bonds offer meaningful income with considerably less interest-rate risk than longer-dated securities, letting investors earn competitive yields without making a large bet on where inflation, the economy, or long-term rates head next.