

Previously, when I looked into Japanese government bonds for individuals, I introduced the mechanism of receiving interest by lending money to the government.
So, if you lend money to a company instead of the government, how much interest can you receive?
That is what we will cover this time: “corporate bonds.”
Personally, even though I knew about the product called corporate bonds, I didn’t really know how many corporate bonds were available for individuals to buy or what kind of yields they offered.
When I looked into it, I found yen-denominated corporate bonds issued in 2026 with annual rates in the 4% range, and even some US dollar-denominated ones offering yields in the high 6% range.
Moreover, these are corporate bonds from well-known companies like SoftBank Group and Meta.
This time, using actual corporate bonds as examples, we will check how much interest you can receive and what kind of risks are involved.
※The conditions for the corporate bonds were confirmed as of October 29, 2026. Sales status and yields of existing bonds fluctuate.
1. What exactly are corporate bonds?
Corporate bonds are bonds issued by companies to borrow money from investors.
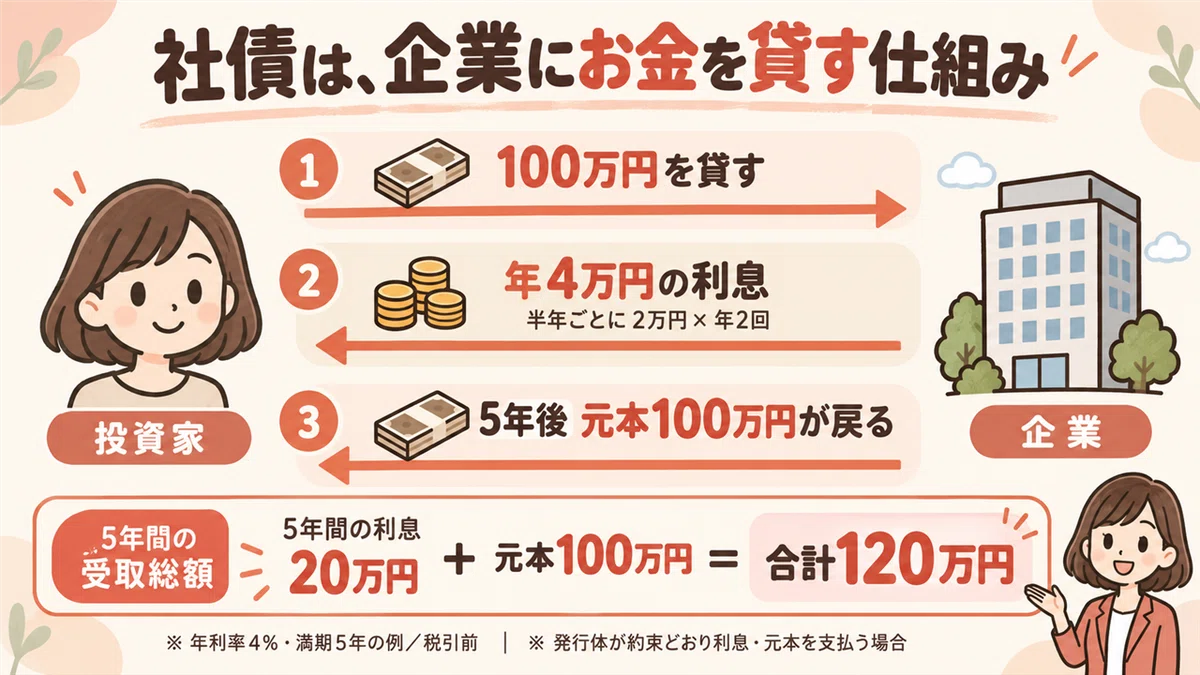
For example, suppose a company issues the following corporate bond:
-
Purchase amount: 1 million yen
-
Interest rate: 4% per year
-
Maturity: 5 years
-
Interest payment: Twice a year
If you purchase this corporate bond, you will receive 20,000 yen every six months, totaling 40,000 yen in interest per year.
The total interest received over 5 years is 200,000 yen. At maturity, the 1 million yen you lent will be returned.
In other words, if the company pays the interest and principal as promised, your 1 million yen will grow to 1.2 million yen in 5 years.
However, in reality, taxes are applied to the interest.
Since interest on corporate bonds is generally subject to a 20.315% tax, if the annual interest is 40,000 yen, the amount after tax is approximately 31,874 yen.
Also, if a company goes bankrupt, there is a possibility that you will no longer receive interest, or that some or all of your principal will not be returned.
The major difference between government bonds and corporate bonds is whether the entity you are lending money to is the government or a corporation.
Now, let’s take a look at some actual corporate bonds.
2. If it’s a yen-denominated corporate bond, how much will you get for 1 million yen?
I have selected three yen-denominated corporate bonds issued in 2026.
SoftBank Group: 4.750% per annum
-
Rating: A (JCR)
-
Term: 7 years
-
Maturity date: September 16, 2033
-
Minimum purchase amount: 1 million yen
If you purchase 1 million yen worth, the annual interest is 47,500 yen. After tax, it is approximately 37,850 yen.
Rakuten Group: 4.370% per annum
-
Rating: A- (JCR)
-
Term: 5 years and 6 months
-
Maturity date: April 28, 2032
-
Minimum purchase amount: 1 million yen
If you purchase 1 million yen worth, the annual interest is 43,700 yen. After tax, it is approximately 34,822 yen.
Sumitomo Mitsui Finance and Leasing: 2.765% per annum
-
Rating: AA (JCR/R&I)
-
Term: 5 years
-
Maturity date: November 5, 2031
-
Minimum purchase amount: 1 million yen
If you purchase 1 million yen, the annual interest is 27,650 yen. After tax, it is approximately 22,034 yen.
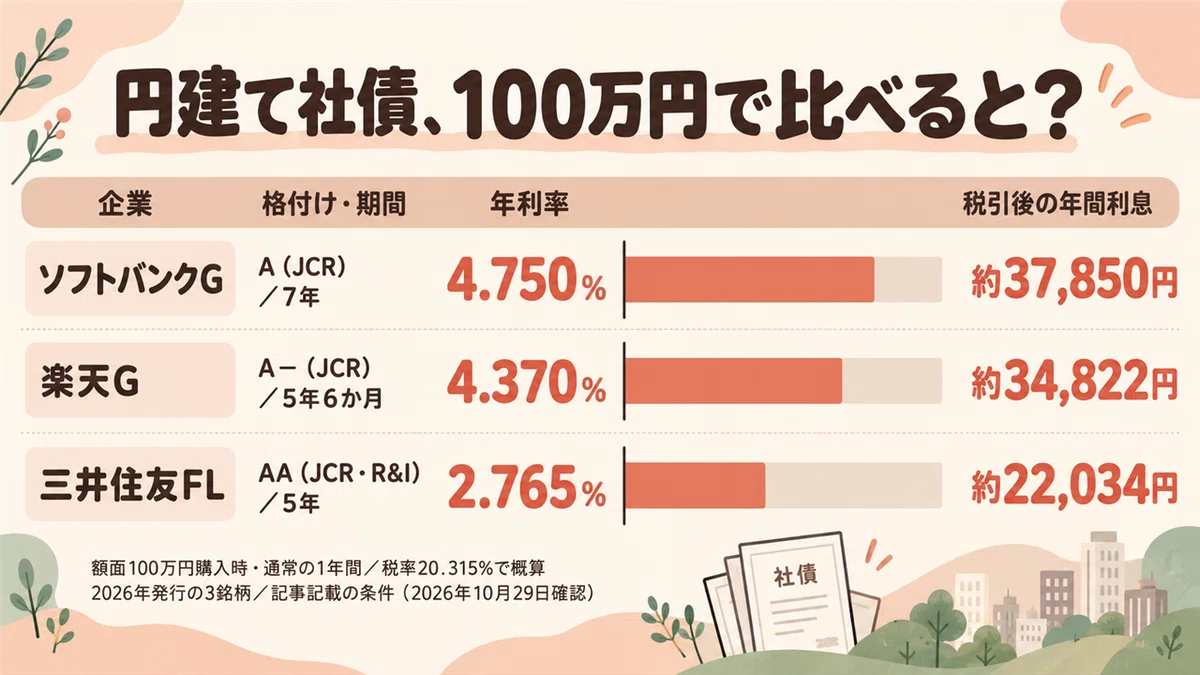
Both are corporate bonds where interest is paid twice a year. The amounts above are for a standard one-year period, and actual interest payments for the first or final periods may differ depending on the duration.
The three issues selected this time are all corporate bonds for individual investors that can be applied for starting from 1 million yen.
The offerings for SoftBank Group and Rakuten Group have ended, but the offering for Sumitomo Mitsui Finance and Leasing began on October 26, 2026.
When compared in this way, there is a significant difference in the interest received even for the same 1 million yen.
Why is that?
3. Does a different credit rating change the interest?
When choosing corporate bonds, you want to check the “credit rating”.
A credit rating is an evaluation by a specialized rating agency of the creditworthiness of a company or similar entity regarding whether they can repay money as promised.
The main credit ratings are listed below in order of highest evaluated creditworthiness.
-
AAA: Highest rating
-
AA: Very high creditworthiness
-
A: High creditworthiness
-
BBB: Lower limit of investment grade
-
BB and below: Speculative rating
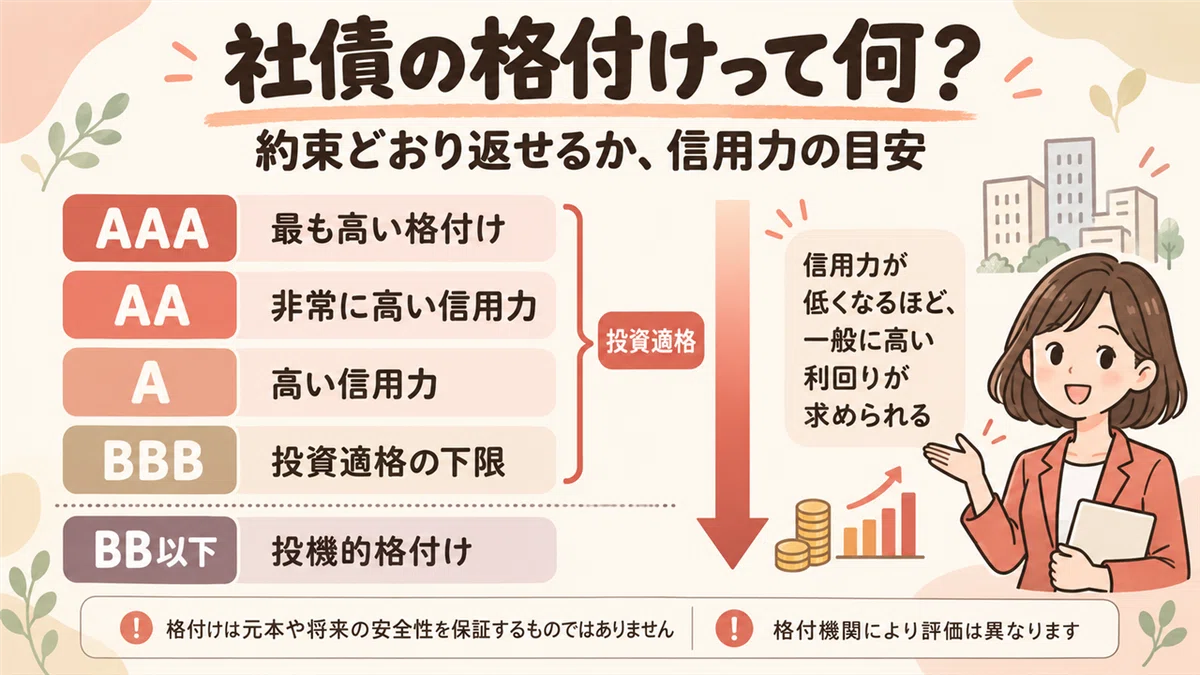
Generally, companies with high creditworthiness can raise funds at relatively lower interest rates.
On the other hand, companies with lower creditworthiness must offer higher interest rates to get investors to lend them money.
Looking at the three companies this time, the AA-rated Sumitomo Mitsui Finance and Leasing was 2.765% per year, and the A-rated SoftBank Group was 4.750% per year.
Of course, interest rates are not determined solely by credit ratings.
The time to maturity of the corporate bond, market interest rates at the time of issuance, and the financial status of each company also have an impact. Additionally, different credit rating agencies may provide different evaluations for the same company.
Even so, checking the credit rating to understand why a corporate bond has a high interest rate when you find one is an important way of thinking when choosing corporate bonds.
Note that a rating of BBB or higher does not guarantee the principal. Credit ratings do not promise future safety and can be downgraded depending on the company’s situation.
4. If it is US dollar-denominated, there are also corporate bonds with yields in the 6% range
Up to this point, I have introduced corporate bonds that you purchase in Japanese yen and receive interest in Japanese yen.
So, what about US dollar-denominated corporate bonds?
US dollar-denominated corporate bonds are bonds where you receive interest and principal in US dollars.
This time, I have selected two from US corporate bonds.
Intel: Reference yield 6.498% per annum
This is a corporate bond from Intel, known as a semiconductor manufacturer.
-
Issuer rating: BBB (S&P)
-
Coupon rate: 4.900% per annum
-
Reference yield to maturity: 6.498% per annum
-
Maturity date: August 5, 2052
-
Remaining period: Approximately 25 years and 9 months
Meta: Reference yield 6.957% per annum
This is a corporate bond from Meta, which operates Facebook and Instagram.
-
Issuer rating: AA- (S&P)
-
Coupon rate: 5.550% per annum
-
Reference yield to maturity: 6.957% per annum
-
Maturity date: August 15, 2064
-
Remaining term: Approximately 37 years and 10 months
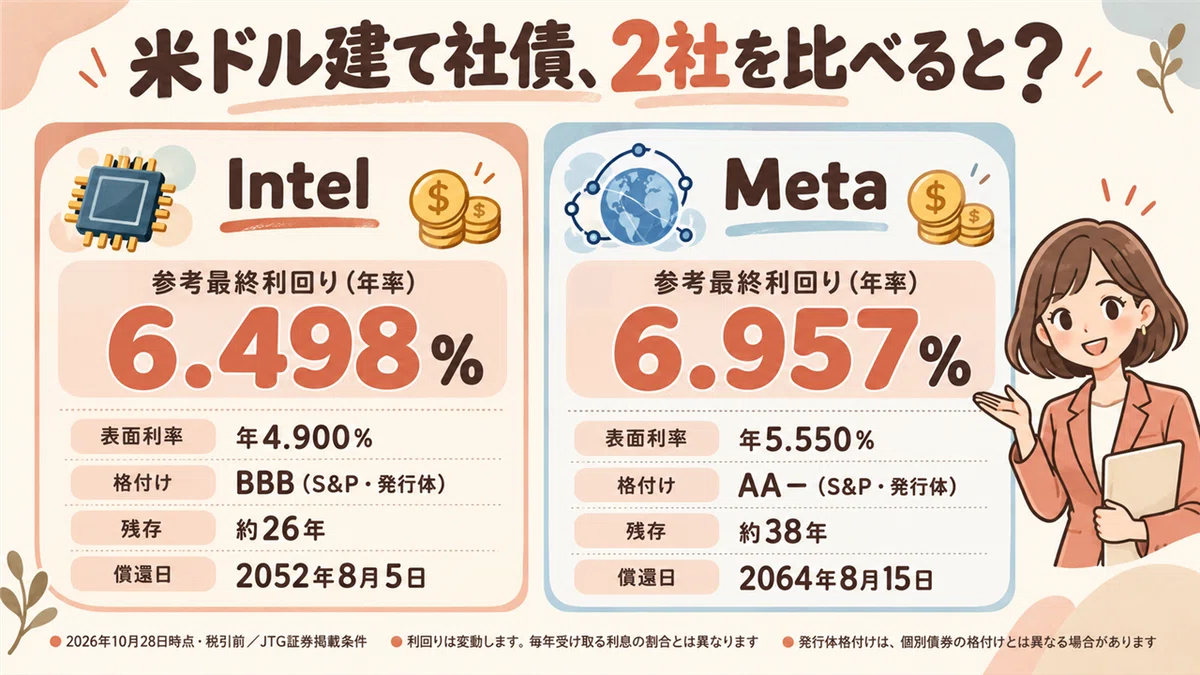
Both are conditions for existing bonds that were listed by JTG Securities as of October 28, 2026.
While the issuer’s credit rating is within the investment-grade range, it is also necessary to check the evaluation of the individual bonds you are purchasing.
Meta has a higher credit rating than Intel, but its reference yield is also higher.
One reason for this is the difference in the remaining term. Meta’s corporate bonds have about 38 years left until maturity.
The longer you lend money, the more you are exposed to future interest rate fluctuations and changes in the corporate business environment, so long-term bonds generally require a higher yield.
Can individuals buy them too?
For the two issues introduced here, the conditions at JTG Securities allowed for purchase starting from a face value of 10,000 US dollars.
However, the actual selling price is lower than the face value, and the amount required to purchase corporate bonds with a face value of 10,000 dollars is approximately 8,000 dollars, excluding accrued interest.
If the exchange rate is 150 yen to the dollar, that would be about 1.2 million yen.
Just like yen-denominated corporate bonds around 1 million yen, there are US dollar-denominated corporate bond products that individuals can purchase.
Of course, the minimum purchase amount varies by securities company, and not all corporate bonds can be bought in small amounts.
Coupon rate and yield are different
You might be a little puzzled here.
Meta’s corporate bonds have a coupon rate of 5.550%, but the yield to maturity is 6.957%.
Why is that?
This is because you can buy corporate bonds for less than their face value.
For example, if you buy a bond with a face value of 100 dollars for 80 dollars and receive 100 dollars back at maturity, a profit of 20 dollars is generated.
The yield to maturity is calculated by taking into account both the interest received during that period and this redemption profit.
This Meta corporate bond was also sold at a price of $81.284 per $100 face value.
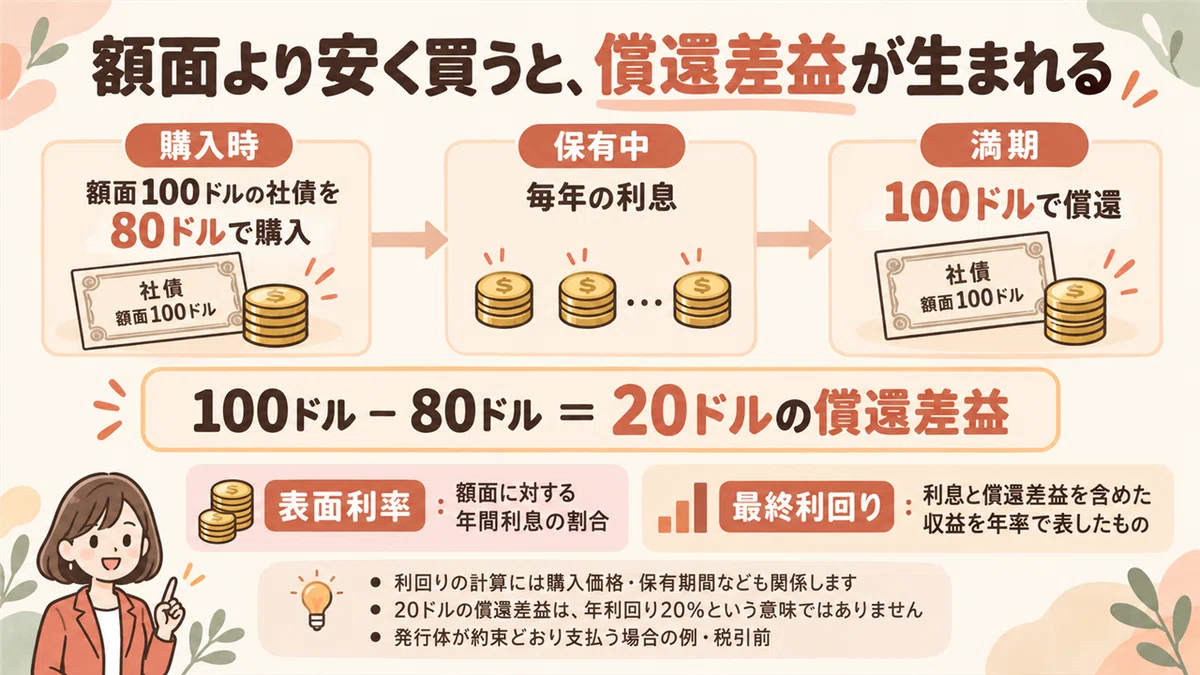
In other words, a yield to maturity of 6.957% does not mean that 6.957% interest is paid in cash every year.
It is a figure that represents the annualized return if the bond is not sold midway and is redeemed at maturity as scheduled.
5. What are the risks associated with high yields?
Looking at it this way, long-term US dollar-denominated corporate bonds feel attractive.
However, there are risks you should check before purchasing.
1. Risk of corporate bankruptcy
Unlike bank deposits, corporate bonds do not guarantee the principal.
If a company goes bankrupt, you may not get your principal back.
Even if a company is a famous large corporation now, it is impossible to accurately predict its management situation 20 or 30 years from now.
Therefore, when choosing corporate bonds, you need to check not only the yield but also the credit rating and the company’s financial status.
2. Possibility of loss if sold midway
In principle, if you hold a corporate bond until maturity, you will receive the specified redemption amount as long as the issuer makes the payments as promised.
However, the price at which you sell it midway changes depending on market conditions.
For example, what happens if, after you buy a 4% annual interest bond, newly issued bonds of a similar level start paying 6% interest?
Since the new bonds are more attractive, it becomes difficult to find a buyer for the 4% bond unless you lower its price.
In general, the longer the remaining term of a bond, the greater the impact of interest rate fluctuations on its price.
This is something to be particularly careful about with long-term corporate bonds like the Meta and Intel ones mentioned here.
Also, you cannot always sell corporate bonds at your desired price whenever you want to.
3. US dollar-denominated bonds also carry exchange rate risk
With US dollar-denominated corporate bonds, even if the company pays as promised, the amount received in yen may decrease due to a stronger yen.
For example, if you exchange 10,000 dollars into yen when the rate is 150 yen to the dollar, you get 1.5 million yen.
However, if the rate becomes 120 yen to the dollar, that same 10,000 dollars will only be worth 1.2 million yen.
Just by the yen becoming stronger, the value in yen terms decreases by 300,000 yen.
Of course, conversely, if the yen becomes weaker, the amount received in yen terms will increase.
In addition to the high dollar-denominated yield, you should also consider whether you will use that money in yen or keep it in US dollars in the future.
6. Where can you buy corporate bonds?
Corporate bonds can be purchased through securities companies.
Broadly speaking, there are “newly issued bonds” that are newly issued and “existing bonds” that have already been issued.
The three yen-denominated issues introduced this time are newly issued bonds, and the two US dollar-denominated issues are existing bonds.
You apply for newly issued bonds during the offering period. Popular issues may sell out before the offering period ends.
On the other hand, for existing bonds, you choose from the issues being sold by the securities company. However, prices and yields fluctuate, and you cannot always purchase the issue you want.
When purchasing, it is a good idea to check at least the following items.
-
Issuing company and credit rating
-
Coupon rate and yield to maturity
-
Remaining time until maturity
-
Minimum purchase amount
-
Risks of mid-term sale or exchange rate fluctuations
Note that if you are considering long-term investment for 20 or 30 years in yen, ultra-long-term Japanese government bonds are also an option.
Recently, some securities companies have started allowing individuals to purchase ultra-long-term government bonds with small amounts of money.
Summary | Corporate bonds are also an option
This time, I looked into yen-denominated corporate bonds and US dollar-denominated corporate bonds.
There were yen-denominated corporate bonds for individuals issued in 2026 with annual yields in the 4% range, and there were also examples of US dollar-denominated bonds offering final yields in the high 6% range.
Of course, there is a reason for high yields.
There are corporate credit risks, the length of the remaining term, price fluctuations if sold mid-term, and for US dollar-denominated bonds, there is also currency risk.
Even so, what left an impression on me after looking into this was that individuals can directly purchase corporate bonds from well-known companies.
For those who have only considered government bonds or bank deposits until now, this might be a somewhat surprising option.
While you should avoid jumping in based solely on yield, if you understand how they work and what to be careful about, it seems like one more option to consider when thinking about how to manage your money.
Reference Materials
-
SoftBank Group, “Notice Regarding Determination of Terms for the 70th Unsecured Straight Bonds” (September 4, 2026)
-
Nomura Securities, “Rakuten Group, Inc. 26th Unsecured Corporate Bonds” (October 2026)
-
Monex, Inc., “Sumitomo Mitsui Finance and Leasing Company, Limited 58th Unsecured Corporate Bonds” (October 2026)
-
JTG Securities, “Foreign Bond and Existing Bond Handling Information” (as of October 28, 2026)
-
National Tax Agency, “Taxation of Interest Income”