

By
Nguyen Thoan, Minh Hue
Sat, July 13, 2024 | 8:15 am GMT+7
Credit rating is not a bottleneck hindering the development of Vietnam’s corporate bond market. Rather, it is the key to making the market transparent, thereby enhancing investor confidence, said Phung Xuan Minh, chairman of Saigon Ratings, the first credit rating agency in the country.
Minh also sees positive signs of the country moving towards a transparent, sustainable bond market.
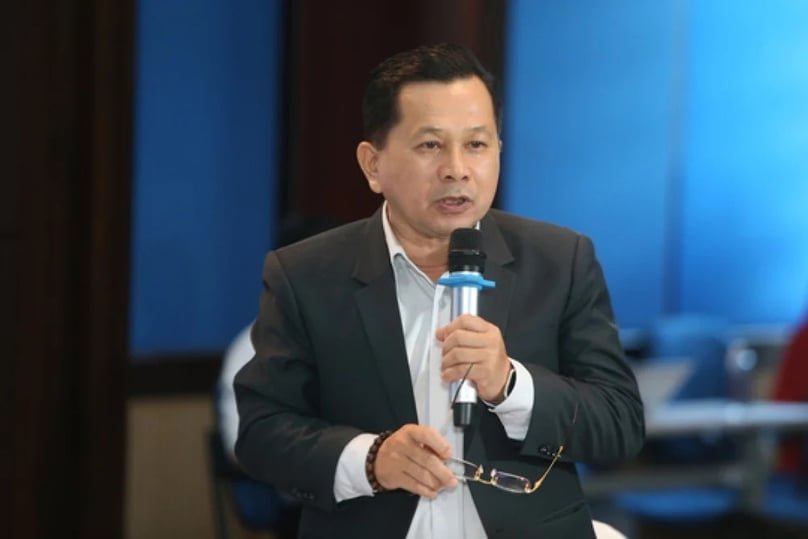
Phung Xuan Minh, chairman of Saigon Ratings. Photo courtesy of Voice of Vietnam.
Regulations on credit ratings for private placement bond issuers in the government’s Decree 08 expired on December 31, 2023. What are some of the salient developments that have happened since?
On January 1, 2024, regulations requiring credit rating results for some bonds took effect. In addition to the VND11 trillion ($432.73 million) worth of bonds issued via public offerings, all with credit ratings, about 4.2% of the remaining VND110 trillion ($4.38 billion) of private placement bonds were also rated.
These are very positive signs of movement towards a transparent and sustainable bond market.
I see five main reasons for the corporate bond market’s recovery in the first six months of this year.
Firstly, market confidence has returned, gradually. The handling of two bond scandals involving real estate developers Tan Hoang Minh Group and An Dong Investment Group JSC, a subsidiary of Van Thinh Phat Group, has helped in this process. State management agencies have succeeded in preventing a system collapse.
Secondly, due to the drastic actions taken by authorities, market players were forced to rectify and begin complying with regulations. Consulting organizations became more responsible as they feared inspections by the Ministry of Finance. This also contributed to making the market healthier, boosting confidence among investors.
Thirdly, statistical data shows that the economy is recovering well and is forecast to be more positive in the remaining half of the year, leading to a rebound in capital demand.
Fourthly, the concerned ministries have basically removed the bottlenecks for many projects, also leading to increased capital needs.
Fifthly, some businesses who could not obtain bank loans without collateral have turned to mobilizing capital from bonds with attractive coupon rates of 10-12% per year.
Another observation I want to make is that credit rating has not been a ‘bottleneck’ hindering the bond market’s progress. The problem lies in investor confidence and economic recovery. The number of bonds that Saigon Ratings has rated in the first six months of this year is probably equal to the combined figure of the last five years.
So do you see better prospects for the corporate bond market in the second half of the year? Will stricter regulations in Decree 65 affect bond issuance activities?
At Saigon Ratings, we feel that the most difficult and challenging period for the corporate bond market has passed. Investor confidence has returned.
This time, with a lot of idle money and low bank interest rates, investors will want to switch from the deposit channel to bonds, particularly if they find it safe with the supervision and management of the government.
Demand in the economy is expected to be high in the last six months towards meeting the H2 credit growth target of 7-7.5%, not to mention businesses needing capital to meet export orders. The growth of public investment and real estate will push up the construction industry, which is very thirsty for medium and long-term capital.
As businesses have recovered and stabilized, a new cycle will come for the corporate bond market. Saigon Ratings has ranked many bonds and consulting companies are also preparing for a series of bond issuance plans in the third and fourth quarters of 2024.
I think that problems for the corporate bond market do not lie in the government’s Decree 65. It has to do with the market. Identifying the real problems will help the market recover in the right direction.
It’s encouraging that the rate of public offering of bonds has reached 9%, compared to the previous 4-6%. How can credit ratings help the bond market?
When the government issued Decree 65 in 2022, everyone thought that credit ratings would cause difficulties and hinder the bond market, affecting issuance volume and increasing costs for enterprises.
However, I think credit rating contributes to market transparency and promotes sustainable market development in accordance with good international practices.
Credit rating helps develop the corporate bond market in three aspects.
Firstly, it helps investors know which bonds are trustworthy and recognize whether a business is a ghost company or a backyard company of someone.
Secondly, credit rating increases information transparency in the market, thereby stimulating demand and making investors feel secure in switching from other investment channels to bonds.
Thirdly, it helps promote public bond offerings. This is in line with international practice.
The world encourages public offerings of bonds because they are strictly managed and of higher quality. In international practice, credit rating for bonds is mandatory for the first 2-3 years of operations.
Once a rating culture is established, it will become indispensable in the market. Any product that does not have a credit rating will be considered fake, counterfeit, or poor quality; and forced to offer higher coupon rates because of greater risk.
My assessment is that enforcement of Decree 65 will follow international practices. Let me repeat: credit rating will help increase investor confidence as well as the evaluation of investments according to investors’ risk appetites. Businesses will not incur costs…In fact, high credit ratings will help good businesses reduce capital costs.
According to the Ministry of Finance, a total of 41 businesses in Vietnam issued VND110.2 trillion ($4.34 billion) worth of private placement corporate bonds in the year to June 21, 2.6 times more than the same period in 2023.
Of the total, credit institutions accounted for 63.2% (VND69.6 trillion or $2.74 billion) and real estate businesses 28.6% (VND31.5 trillion).
The average coupon rate was 7.41% per year and the average issuance term was 3.78 years. About 14.5% of issued bonds were based on collateral.