
Indian equity markets have been in a phase of indecision over the past 15–18 months. After the sharp correction that began in September 2024, broader market indices have largely oscillated within a range, offering little conviction to investors either way. In this backdrop, many investors prefer to temporarily step aside and wait for the market to give a green signal before deploying fresh money.
Investors wanting to deploy funds for about a year while earning better returns than a savings account, several categories of debt-oriented mutual funds and hybrid funds offer viable options. These funds prioritise liquidity, relatively low volatility and modest returns, making them suitable for parking money while waiting for opportunities in the equity market.
The most relevant categories include arbitrage funds, liquid and overnight funds, ultra-short duration funds, low-duration funds and money market funds.
These funds can also be useful for investors who plan to gradually shift into equity funds through systematic transfer plans (STPs). However, portfolio quality, expense ratio and exit load are key factors investors should examine before investing in these funds.
Arbitrage funds
Arbitrage funds exploit price differences between the cash market and the futures market. For instance, if a stock trades at ₹100 in the cash market and ₹101 in the futures market, the fund buys the stock in the cash segment and simultaneously sells the futures contract. When the contract expires, the price difference is locked in as profit. These funds also employ index futures and covered call strategies.
Because these trades are hedged, arbitrage funds carry very limited directional equity risk. Returns largely depend on the arbitrage spreads available in the market and short-term interest rates.
The key advantage is taxation. Since these funds maintain equity exposure above 65 per cent through hedged positions, they are taxed as equity funds. If held for more than one year, gains qualify for long-term capital gains taxation.
Performance, measured by one-year rolling returns calculated from the last five years of direct plans, shows that funds in this category delivered an average return of 5.9 per cent. Their one-year returns ranged between 2 per cent and 8.3 per cent during the period.
Investors should note that arbitrage spreads can compress when liquidity in the derivatives market tightens. Therefore, returns can vary depending on market conditions. Still, for investors looking to park money for about 12 months, arbitrage funds remain one of the most tax-efficient options.
Expense ratios for regular plans range from 0.6 to 1.6 per cent, while direct plans typically charge between 0.1 and 0.4 per cent. Exit loads range from nil to about 0.5 per cent for holding periods between seven days and one month.
Liquid and overnight funds
Liquid funds invest in money market instruments such as treasury bills, commercial papers and certificates of deposit with maturities of up to 91 days. These funds also offer an instant redemption facility that enables investors to withdraw a portion of their investment, usually up to ₹50,000 or 90 per cent of the folio value (whichever is lower), with funds credited to the bank account within minutes through IMPS.
The performance of liquid funds largely tracks short-term interest rates in the economy. Based on one-year rolling returns over the past five years for direct plans, the category delivered an average return of 5.6 per cent. Returns ranged between 2.9 per cent and 7.5 per cent during the period.
Expense ratios for regular plans range from 0.13 to 0.54 per cent, while direct plans typically charge between 0.06 and 0.23 per cent. Exit loads are usually minimal, up to about 0.007 per cent for holdings redeemed within seven days.
Overnight funds, similar to liquid funds, invest in securities that mature in one day. Because the maturity is extremely short, these funds carry virtually no interest-rate risk or credit risk. They are widely used by institutions and treasury managers for very short-term parking of funds. However, liquid funds typically offer slightly higher returns than overnight funds while still maintaining high liquidity and relatively low volatility.
Ultra-short duration funds
Ultra-short duration funds invest in instruments with a Macaulay duration of three to six months. Because they take slightly higher duration exposure than liquid funds, they may offer marginally better yields.
These funds typically invest in high-quality corporate bonds, commercial papers and money market instruments. The short maturity profile ensures that interest-rate changes do not significantly erode returns over short holding periods.
Performance measured by one-year rolling returns over the last five years for direct plans shows that the category delivered an average return of 6.6 per cent. Their one-year returns ranged between 3 per cent and 8.8 per cent during the period.
Expense ratios for regular plans range from 0.3 to 1.4 per cent, while direct plans typically charge between 0.13 and 0.5 per cent. Exit loads are generally nil across most funds in the category, according to ACEMF data.
However, investors should pay close attention to portfolio quality. Credit events in debt funds in the past have highlighted the importance of choosing funds that emphasise high-rated instruments and maintain a conservative portfolio construction.
Low-duration funds
Low-duration funds extend the maturity profile further, with Macaulay duration typically ranging between six and 12 months. These funds invest across corporate bonds, government securities and money market instruments.
Because of the slightly longer duration, they are somewhat more sensitive to interest-rate movements than ultra-short duration funds.
Performance measured by one-year rolling returns over the last five years for direct plans shows that the category delivered an average return of 6.8 per cent. Their one-year returns ranged between 2.5 per cent and 9.5 per cent during the period.
Expense ratios for regular plans range from 0.4 to 1.2 per cent, while direct plans typically charge between 0.17 and 0.46 per cent. Exit loads are generally nil across funds in this category, according to ACEMF data. As with other debt funds, investors should pay close attention to portfolio quality.
Money market funds
Money market funds focus on investing in high-quality money market instruments such as treasury bills, commercial papers and certificates of deposit with maturities of up to one year.
Compared with liquid funds, money market funds may generate slightly higher returns by taking exposure to instruments with somewhat longer maturities. However, they still maintain relatively low interest-rate sensitivity.
Performance measured by one-year rolling returns over the past five years for direct plans shows that the category delivered an average return of 6.6 per cent. Their one-year returns ranged between 3 per cent and 8.6 per cent during the period.
Expense ratios for regular plans range from 0.22 to 0.9 per cent, while direct plans typically charge between 0.08 and 0.25 per cent. Exit loads are generally nil across funds in the category, according to ACEMF data.
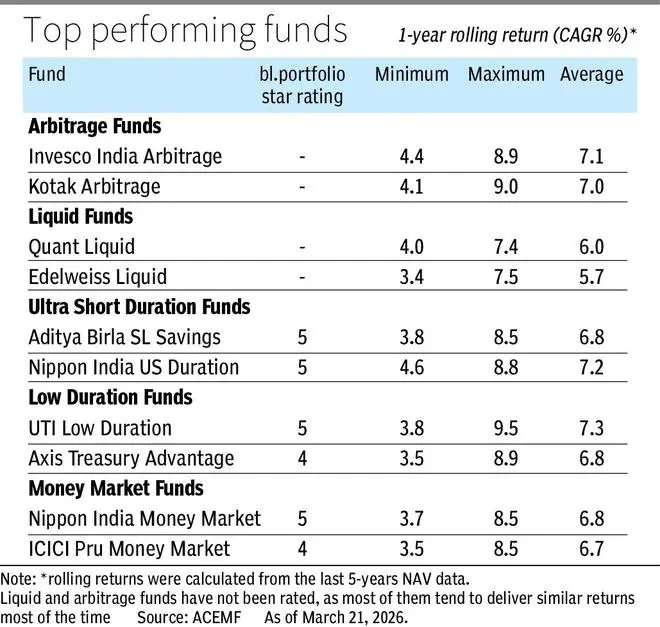
For debt funds, gains are added to the investor’s income and taxed at the applicable slab rate (for investments made after April 2023). The accompanying table lists the top-performing funds based on one-year rolling returns across the aforementioned categories.
Published on March 14, 2026