Navigating the Uncertain With Defined Outcome ETFs
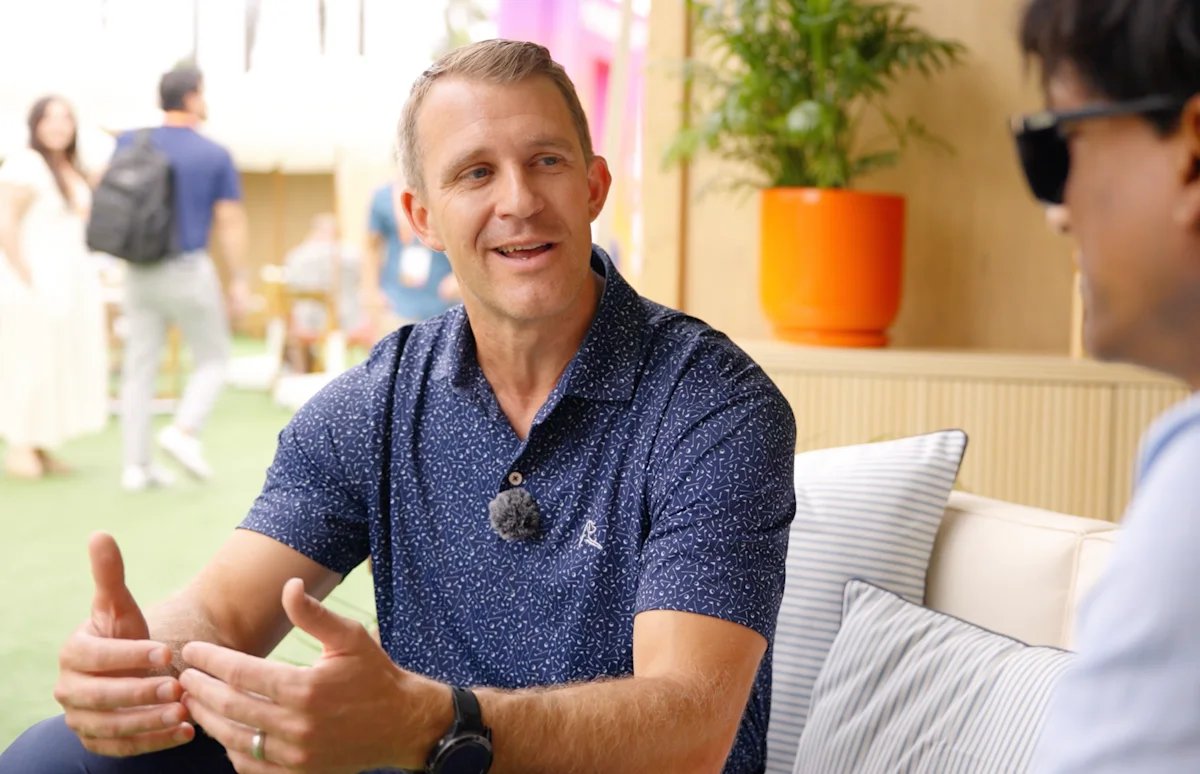
Andrew Nelson smiles while talking with Sumit Roy at the ETF Oasis.
As investor interest in defined outcome ETFs grows, Andrew Nelson, Director, Product Strategy, Innovator from Goldman Sachs Asset Management, sat down at the ETF Oasis with ETF.com’s Sumit Roy to talk the growth of the category in the last eight years. The following is a transcript of their conversation.
Defined Outcome ETF Adoption Grows
Sumit Roy: Andrew, how are you doing? So good to see you.
Andrew Nelson: I’m well Sumit, thanks for having me.
Sumit Roy: So, you’re with Innovator, which is now under Goldman, and I want to talk about that. But first, let’s jump straight into defined outcome ETFs. Innovator pioneered this a handful of years ago, almost eight years ago now. But they’re still seeing continued adoption. They were niche back when they first launched, but now they’re a big category. Why do we continue to see such adoption with these ETFs?
Andrew Nelson: Well, it’s a great question. I think you could go a couple different directions with the answer. On one hand, it’s the common response of democratizing investment strategies that have been available outside the ETF wrapper for institutional investors and that now is in the ETF wrapper. Defined outcome, options‑based investing has been available a long time. The ETF wrapper makes it easier to access, so the access point is one: liquidity, transparency, and so on.
There’s also a desire to have certainty in portfolios, and to take that simplicity of the ETF and to know ahead of time what my parameters are, what my upside could be, what my downside could be. That is really powerful in practice. So you have a large market that has been trying to access that outcome and payoff profile for a long time, and now it’s moving into the ETF wrapper. Just last year alone, I think you saw something like $285 billion in growth in protection annuity sales. Those will continue, but they’re trying to achieve a similar objective to defined outcome or buffer ETFs. And we only had, as an industry, $11 billion in flows last year. So it’s growing. We see those two mismatched numbers prove the fact that there’s a lot more that could happen from the tailwind perspective to help us continue to grow and provide value to investors’ portfolios.
Sumit Roy: Sounds like they’re just scratching the surface.
Andrew Nelson: We think so.
Sumit Roy: 2018, like I said, is when the first ones launched. How have they evolved? We know advisors are using them; those are the primary users of these ETFs now. And has it changed, how they used them back in 2018 versus how they’re using them now in 2026?
Andrew Nelson: It really has. It has evolved, if you will. It hasn’t completely changed. When we launched our products in 2018, the initial go‑to‑market movement was to say, hey, these are a great equity hedge, and they certainly are. But an easy evolution I can cite is that by now, here in 2026, a lot of advisors view a buffer ETF tied to the equity market as a great complement or alternative to even the fixed income instrument. We’re not saying that these are bond ETFs; they’re equity ETFs. But the way you can reduce the volatility profile and add some certainty and some additional equity upside, they really become this unique fixed income sleeve, if you will.
That’s a major evolution that we’ve seen grow quite a bit. You also see the use cases as a whole morph and change. While you mentioned the retail investor to start, we now see institutional uses emerging, things like pensions and endowments are beginning to look at buffer ETFs as well for a way to control risk in a very liquid and easy fashion. Both those elements, that fixed income view as well as additional adoption, have really expanded the pie also.
Sumit Roy: Also, another new category that Innovator seems to be wading into is the autocallable ETF. What do you think about this? Is it related to buffer ETFs? Does it complement them? Is it an alternative? What do you think?
Andrew Nelson: We think it’s an extension of our expertise, and by that I mean risk‑managed, options‑based portfolios, derivative‑based portfolios. How do we best bring that to the market? There is a need right now for income in clients’ portfolios. The autocallable income space is newish, but it’s quickly growing. There are ways we can take some of our more risk‑managed dollars, put them in the equity market for potentially higher income upside, and get that in the ETF wrapper.
Right now we have two of these autocallable ETF offerings. One is a high income product yielding north of 10% on a monthly basis, and one is almost 14%. To be able to offer that to clients in a unique ETF wrapper, we think, is a great value proposition. And, to your point, it is an extension of what we already do, taking the best of our DNA and this innovative mindset of how can we continue to expand, and putting it into the ETF wrapper we think that goes a long way.
Sumit Roy: And you guys have done tremendously well. So well, in fact, that you got acquired by Goldman Sachs recently. So what does that mean for Innovator? The new ownership, does it change what advisors can expect of the platform?
Andrew Nelson: No. In fact, I’ve used the mantra that we’re better together as how I go out to the market. Goldman purchasing Innovator ETFs, and the transaction closed in April of this year, 2026, is only additive. It’s fuel on the fire of what we’ve already been doing. The mandate from Goldman has been: continue with what you have, expand, go quicker, continue to move in that way.
So you’ll continue to see innovative product launches from our side. You’ll see continued resourcing and expansion in that way. We really think it’s a benefit that we are better together, both in that institutional caliber and nature of Goldman Sachs with the innovative upstart nature of Innovator ETFs really marry nicely. And even at this conference today, you’ll see the additional expanded brand awareness that comes from Goldman Sachs being a part of Innovator, and Innovator being part of Goldman Sachs.
Sumit Roy: Andrew, it’s been an absolute pleasure.
Andrew Nelson: Thank you. Thanks so much. Appreciate your time.
Disclosures
The Funds have characteristics unlike many other traditional investment products and may not be suitable for all investors. For more information regarding whether an investment in the Fund is right for you, please see “Investor Suitability” in the prospectus.
The outcomes that the Fund seeks to provide may only be realized if you are holding shares on the first day of the Outcome Period and continue to hold them on the last day of the Outcome Period, approximately one year. There is no guarantee that the Outcomes for an Outcome Period will be realized or that the Fund will achieve its investment objective.
The Funds face numerous market trading risks, including active markets risk, authorized participation concentration risk, buffered loss risk, cap change risk, capped upside return risk, correlation risk, liquidity risk, management risk, market maker risk, market risk, non-diversification risk, operation risk, options risk, trading issues risk, upside participation risk and valuation risk. For a detail list of fund risks see the prospectus.
The investment results of an autocallable note depends on the performance of the reference asset(s), with the payouts being in the form of coupon payments rather than capital appreciation related to the reference asset. Fund shareholders can lose money by investing in the Funds. There can be no assurance that the Funds’ investment objectives will be achieved.
The Funds face numerous principal risks, including autocallable strategy risk, autocallable returns risk, barrier risk, call risk, market indices risk, equity securities risk, smaller companies risk, derivatives risk, counterparty risk, credit risk, OTC derivatives risk, FLEX options risk, box spread risk, swap agreements risk, distribution tax risk, U.S. government securities risk, money market fund risk, concentration risk, cybersecurity risk, management risk, market risk, non-diversification risk, authorized participant concentration risk, cash transactions risk, market maker risk, operational risk, premium/discount risk, trading issues risk, tax risk, and valuation risk, among others. For a detailed list of Fund risks, see the prospectus.
Autocallable Strategy Risk Through its use of Autocallable Instruments, the Funds are subject to various risks associated with the return profile of autocallable strategies, including, but not limited to, Autocallable Returns Risk, Barrier Risk, and Call Risk that have been detailed further below.
Autocallable Returns Risk Autocallable instruments differ in various ways from traditional debt securities. Autocallable Instruments do not guarantee a return of principal and limit the positive investment return that can be achieved through the operation of the Maturity Barrier Level, which if triggered by the worst-performing reference asset, subjects the Funds to the losses of such reference asset. Further, the Funds do not participate in any upside gain of any reference asset, and if the autocall feature of an instrument is triggered, the Funds would forego any remaining coupon payments. The coupon payments of Autocallable Instruments are not linked to the performance of the reference asset at any time other than on the Maturity Date and Coupon Observation Dates. Moreover, because the Autocallable Instruments do not participate in any upside performance of the reference asset, the Fund’s positive returns are limited to the Coupon Payments. If the autocall feature is triggered, the Funds will forego future Coupon Payments and any positive returns may be limited.
The Fund’s investment objectives, risks, charges and expenses should be considered carefully before investing. The prospectus and summary prospectus contain this and other important information, and it may be obtained at innovatoretfs.com. Read it carefully before investing.
Investing involves risk. Principal loss is possible. All rights reserved. Innovator ETFs are distributed by Foreside Fund Services, LLC.
The following marks: Accelerated ETFs®, Accelerated Plus ETF®, Accelerated Return ETF®, Barrier ETF®, Buffer ETF™, Defined Income ETF™, Defined Outcome Bond ETF®, Defined Outcome ETFs™, Define Your Future®, Enhanced ETF™, Floor ETF®, Innovator ETFs®, Leading the Defined Outcome ETF Revolution™, Managed Buffer ETFs®, Managed Outcome ETFs®, Step-Up™, Step-Up ETFs®, Defined Protection ETF®, 100% Buffer ETFs™ and all related names, logos, product and service names, designs, and slogans are the trademarks and registered trademarks of Goldman Sachs, its affiliates or licensors. Use of these terms is strictly prohibited without proper written authorization.