
I have surplus cash to spread around and am looking for ways to pass on as much of it tax-free as possible
I have been looking at the gifting rules and the sums you can give away – but I want to hand over more than £3,000 each year.
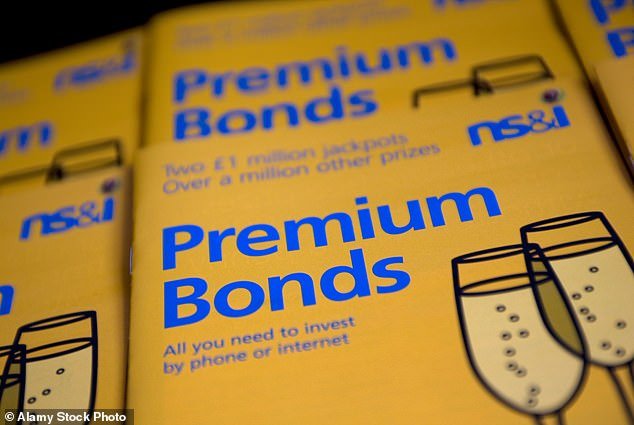
Prizes won in the Premium Bonds prize draw are tax free so could I gift Premium Bonds for each of my four grandkids, putting the maximum £50,000 in them for them to accumulate prizes tax free?
I don’t intend to cash the prizes in for myself but rather use it as a way to pass on money to my relatives tax-free once they turn 16 and are able to manage the account for themselves.
Helen Kirrane of This is Money replies: One of the biggest draws of Premium Bonds is that unlike regular savings accounts, any prizes won are tax free.
You can open them for your relatives, but it is not as simple as funnelling the maximum £50,000 into Premium Bonds for your grandchildren and being able to pass on all of the money to them tax free.
For expert advice on your situation, we spoke to Shaun Moore, tax and financial planning expert at Quilter and Roger Clarke, chartered financial planner at The Private Office
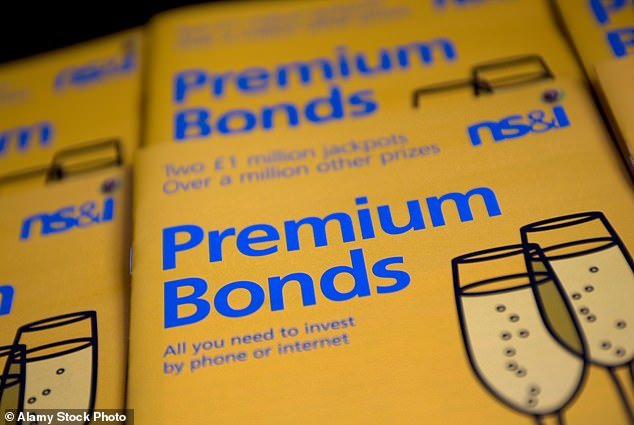
Premium Bonds are held by 24m people and offer prizes ranging from £25 to £1m tax free
Shaun Moore, tax and financial planning expert at Quilter replies: Premium Bonds can be a useful tool in financial planning, not least because any prizes won are entirely tax-free.
However, when it comes to using them to pass on wealth to younger generations, there are important rules and limitations to bear in mind.
While you can purchase Premium Bonds on behalf of your grandchildren, they must be under 16 and the bonds must be held in their name via a parent or legal guardian.
You can gift up to £50,000 per child in theory, matching the individual Premium Bond holding limit, but practically, you’d be constrained by both parental consent and the gifting rules for inheritance tax purposes.
From a tax perspective, the Premium Bond prizes remain tax-free regardless of who wins them.
However, simply gifting money into Premium Bonds does not remove the value of that gift from your estate immediately.
Unless the gift qualifies for one of the IHT exemptions, such as the £3,000 annual exemption or regular gifts out of surplus income, it will remain a potentially exempt transfer and could be subject to inheritance tax if you were to die within seven years.
It’s also important to understand that Premium Bonds cannot be transferred into a Junior Isa at a later date. They are separate products.
Once the child turns 16, they can take control of the Premium Bonds, but the capital remains in NS&I’s savings vehicle unless cashed in.
If your aim is to pass on wealth tax-efficiently, Premium Bonds can help preserve tax-free status on winnings, but they don’t shelter the capital value from IHT on their own.
Combining modest Premium Bond gifts with structured use of Isas, pensions, or trusts may provide a better long-term strategy for intergenerational planning.
Roger Clarke, chartered financial planner at The Private Office replies: The only exemption for passing on money tax free is the £3,000 gifting rule, or gifts out of surplus income.
The rules for gifts out of surplus income are more opaque than the other rules and, for this reason, it is probably the most underutilised method of gifting.
However, in certain circumstances, it can be the most effective method of all, particularly with individuals with large incomes.
Most people are aware of the fact that gifts can be made, and it is necessary to survive for seven years before the gift is considered to be outside of the estate.
This is the ‘Lifetime Gifts’ and for non-trust based gifts, these are referred to as Potentially Exempt Transfers or PETs. Gifts to Absolute/Bare Trusts are also PETs.
The Gifting from Income rules mean that gifts which qualify for this type of gifting are immediately exempt and the seven-year rule does not apply.
In essence, gifting from income is permissible for net excess income that is considered to be surplus to requirements after the donor’s regular expenditure needs have been met.
In other words, the gifts must not, in any way, impact on the gift-givers standard of living.
There is no upper limit on the amount of gifting that can be made.
The gifts must also form part of a regular pattern of the gift-giver’s payments.
There also needs to be evidence of this (e.g. a standing order).
HMRC do not specify over what period the gifting needs to be but, generally speaking, three to four years is considered to be necessary.
Single, one-off gifts are unlikely to qualify but, even then, not necessarily if the single gift can be seen as part of a regular pattern.
Because the rules are opaque it is imperative that all gifts must be clearly documented, especially as the exemption can only be claimed on death.
This will also be important for the personal representatives or executors who, on death, will be required to complete Form IHT 403 in which all gifts and transfers need to be detailed.
Any regular gifts need to be made from regular income such as earned income; rental income, dividends and pension income.
These are all considered to be income for this purpose but ‘Income’ from investment bonds or Discounted Gift Trusts will not qualify as this is deemed to be capital (albeit regular capital income).
Any gifts made from capital or selling down capital will not qualify and are likely to be PET
SAVE MONEY, MAKE MONEY
Sipp cashback
Sipp cashback
Up to £2,000 cashback until 31 August
.JPG)
5.44% cash Isa
5.44% cash Isa
Rate boosted for three months, then 4.59%
£20 off motoring
£20 off motoring
This is Money Motoring Club voucher
Investing Isa offer
Investing Isa offer
1% back (max £200) when adding £5,000+
.JPG)
No fees on 30 funds
No fees on 30 funds
Potentially zero-fee investing in an Isa or Sipp
Affiliate links: If you take out a product This is Money may earn a commission. These deals are chosen by our editorial team, as we think they are worth highlighting. This does not affect our editorial independence. Terms and conditions apply on all offers.