

The expansion of unrealized losses on yen bonds is being absorbed by the increase in unrealized gains on stocks
When interest rates rise, the price of yen-denominated bonds (yen bonds) held by banks falls, creating unrealized losses. Where and how are these unrealized losses recorded in a bank’s financial results?
Looking at the FY2026 financial results of The Keiyo Bank, Ltd. (8544), the treatment of unrealized losses on yen bonds differs significantly depending on whether they were sold or not. The portion sold is recognized as a loss on the income statement, pushing down core business profit—net business profit—by 85% from 9.96 billion yen in the previous period to 1.47 billion yen. The portion not sold does not pass through the income statement; instead, it is combined with unrealized gains on stocks on the net assets side of the balance sheet. Consequently, the increase in unrealized losses on yen bonds over the past year was absorbed by the increase in unrealized gains on stocks.
Meanwhile, net income for the period reached a record high of 15.8 billion yen. I will verify the reasons why “unrealized losses on yen bonds,” “an 85% decrease in core business profit,” and “record high net income” appear in the same financial results by performing calculations while looking at the pages of the financial results summary. I will explain terms specific to bank financial statements in the order they appear, using the Keiyo Bank materials themselves.
Materials used
The Keiyo Bank, Ltd. (Securities Code 8544) “Financial Results for the Fiscal Year Ended March 31, 2026 [Japanese GAAP] (Consolidated),” disclosed on May 12, 2026. The financial results summary and the “FY2026 Financial Results Presentation Materials” are bound together in a single PDF (35 pages in total).
Since this material does not have page numbers printed on the pages, I will provide both the “PDF page number” and the “page number according to the material’s table of contents” in the text.
The Keiyo Bank is not under a holding company; the listed company itself is the bank. All figures below are for the bank on a non-consolidated basis. Figures in diagrams are in 100 million yen, while the text and tables use millions of yen as per the material’s units; numbers without specified units are in millions of yen.
In this article, “yen bonds” refers to Japanese government bonds, municipal bonds, and corporate bonds held by The Keiyo Bank. On page 14 of the PDF, page 12 of the financial results summary table of contents, under the breakdown of securities in “4. (1) Balance Sheet,” the bank held 496.4 billion yen in government bonds, 192.4 billion yen in municipal bonds, and 77.6 billion yen in corporate bonds as of the end of March 2026. Compared to the 114.3 billion yen in stocks, this is nearly seven times the scale.
Unrealized losses on yen bonds appear in three separate places
First, I will present a map of the conclusion.
In The Keiyo Bank’s financial results summary, unrealized losses on yen bonds appear in the following three places.
The first is yen bonds that have been sold. Once sold, the unrealized loss is finalized as a loss and recorded on the Income Statement (PL). The second is the portion of unsold yen bonds classified as “other securities.” These are evaluated at market value at the end of each period, and the unrealized loss does not pass through the income statement but is recorded in the net assets on the Balance Sheet (BS). The third is bonds such as those “held-to-maturity” intended to be held until maturity, where unrealized losses are recorded neither on the income statement nor in net assets.
Figure 1 illustrates the first case, and Figure 2 illustrates the second. First, let’s look at the overall picture of the income statement in Figure 1.

Adding and subtracting from left to right results in ordinary profit. Starting from green fund profit (interest earnings), it is significantly reduced by red yen bond trading gains/losses, causing net business profit—the profit from core business—to fall to 1.47 billion yen. To the right of the dotted line, outside of core business, blue stock trading gains/losses are added, bringing ordinary profit back to 22.11 billion yen.
Below, I will verify which figures from the financial results summary each bar in this diagram comes from.
A bank’s income statement is arranged differently from that of a general company
First, let’s look at the formal accounting income statement. It is on page 16 of the PDF, page 14 of the financial results summary table of contents, “4. (2) Income Statement.”

The income statements of general companies are arranged in stages: “Net Sales → Gross Profit → Operating Income.” Banks do not follow this structure; instead, they list revenues (ordinary revenues) in the top half and expenses (ordinary expenses) in the bottom half by category, simply calculating the difference as ordinary profit at the end.
Revenues and expenses are paired into the following four groups.
Revenue Item Expense Item Content Fund Operating Revenue 68,990 Fund Procurement Expense 14,029 Interest received from loans and bonds, and interest paid on deposits, etc. Service Transaction Revenue 13,154 Service Transaction Expense 4,976 Transfer fees, investment trust sales commissions, etc. Other Business Revenue 1,713 Other Business Expense 22,229 Mostly gains/losses from trading bonds such as government bonds Other Ordinary Revenue 23,715 Other Ordinary Expense 3,505 Gains/losses from stock trading, provision for allowance for loan losses, etc.
What is important to note here is that the placement of yen bonds and stocks is different. The loss on sale of government bonds, etc., of 21,677 is included in “Other Business Expenses,” while the gain on sale of stocks, etc., of 23,340 is included in “Other Ordinary Revenue.” This difference is the reason behind the situation where “despite record profits, core business profit is down 85%.”
Stage-based profits and terminology used by banks
With this income statement format, it is impossible to tell how much the core business has earned. Therefore, banks reclassify items to create and disclose their own stage-based profit figures. This can be found on page 26 of the PDF, or page 5 of the financial results briefing materials (above the table of contents), under “II-1 Profit and Loss Status (Non-consolidated).” Each bank is assigned a number (No.).

I will explain the terms appearing in this table in order from the top.

Fund profit, service transaction profit, and other business profit are divided into domestic and international operations in the table. The figures above are the totals for both, which are listed on page 23 of the PDF (page 2 of the financial results briefing materials, above the table of contents).
General allowance for loan losses is money set aside to prepare for the possibility that a portion of loans will become unrecoverable in the future, specifically the portion not tied to any particular client. Increasing this provision is an expense, while reversing it is a profit. Keiyo Bank’s provision for this term is -531, where the negative sign indicates a reversal. Looking at “3. Status of Allowance for Loan Losses, etc.” on page 33 of the PDF (page 12 of the financial results briefing materials, above the table of contents), the balance of the general allowance for loan losses has decreased from 8,265 to 7,734, exactly 531. For this reason, the net business profit of 1,468 is higher than the 937 before the provision.
The formula for core net business profit is shown in the notes below the table.
(Note) Core Net Business Profit (No. 20) = Net Business Profit (before provision for general allowance for loan losses) (No. 19) – Gains/Losses on Government Bonds, etc. (No. 24)
Calculating this actually yields 937 – (-19,987) = 20,924. The difference of 1 from the disclosed value of 20,925 is due to rounding down amounts less than one million yen.
Gains and losses from bond trading fluctuate significantly from year to year depending on interest rate movements and the bank’s selling decisions. The concept behind this indicator is that by excluding these, one can understand the true strength of the core business, such as lending and fees.
Calculating gross business profit
Now that the terminology is clear, I will assemble the gross business profit. This is on page 23 of the PDF, page 2 of the financial results briefing materials (above the table of contents), under “I-1 Profit and Loss Status (Non-consolidated).”

Fund profit 54,968 + Service transaction profit 8,177 + Other business profit -20,516 = 42,629. This matches the disclosed value. The first five bars from the left in Figure 1 represent this calculation (other business profit is depicted separately as -19,987 for yen bond trading gains/losses and -529 for foreign exchange, etc.).
What catches the eye here is that the gross business profit of 42,629 is lower than the fund profit of 54,968. Although interest earnings, which are the core of the business, are 55 billion yen, the total earnings are 12.3 billion yen less than that. This is because other business profit is significantly negative due to the loss on the sale of yen bonds.
Core business: Interest earnings have increased
Before diving into the topic of yen-denominated bonds, I will first confirm how rising interest rates affected the core business.
Net interest income increased by 5.7 billion yen compared to the previous fiscal year, a growth rate of 11.4%. Checking the details in the income statement on page 16 of the PDF, interest on loans increased by 11.5 billion yen from 39,338 to 50,828, while interest on deposits also increased by 8 billion yen from 3,627 to 11,659. This means that the increase in interest income from loans exceeded the increase in interest expenses on deposits.
This relationship becomes clear when looking at yields. Please refer to the domestic business segment on page 7 of the financial results presentation materials (page 28 of the PDF), titled “3. Interest Margins (Non-consolidated).”
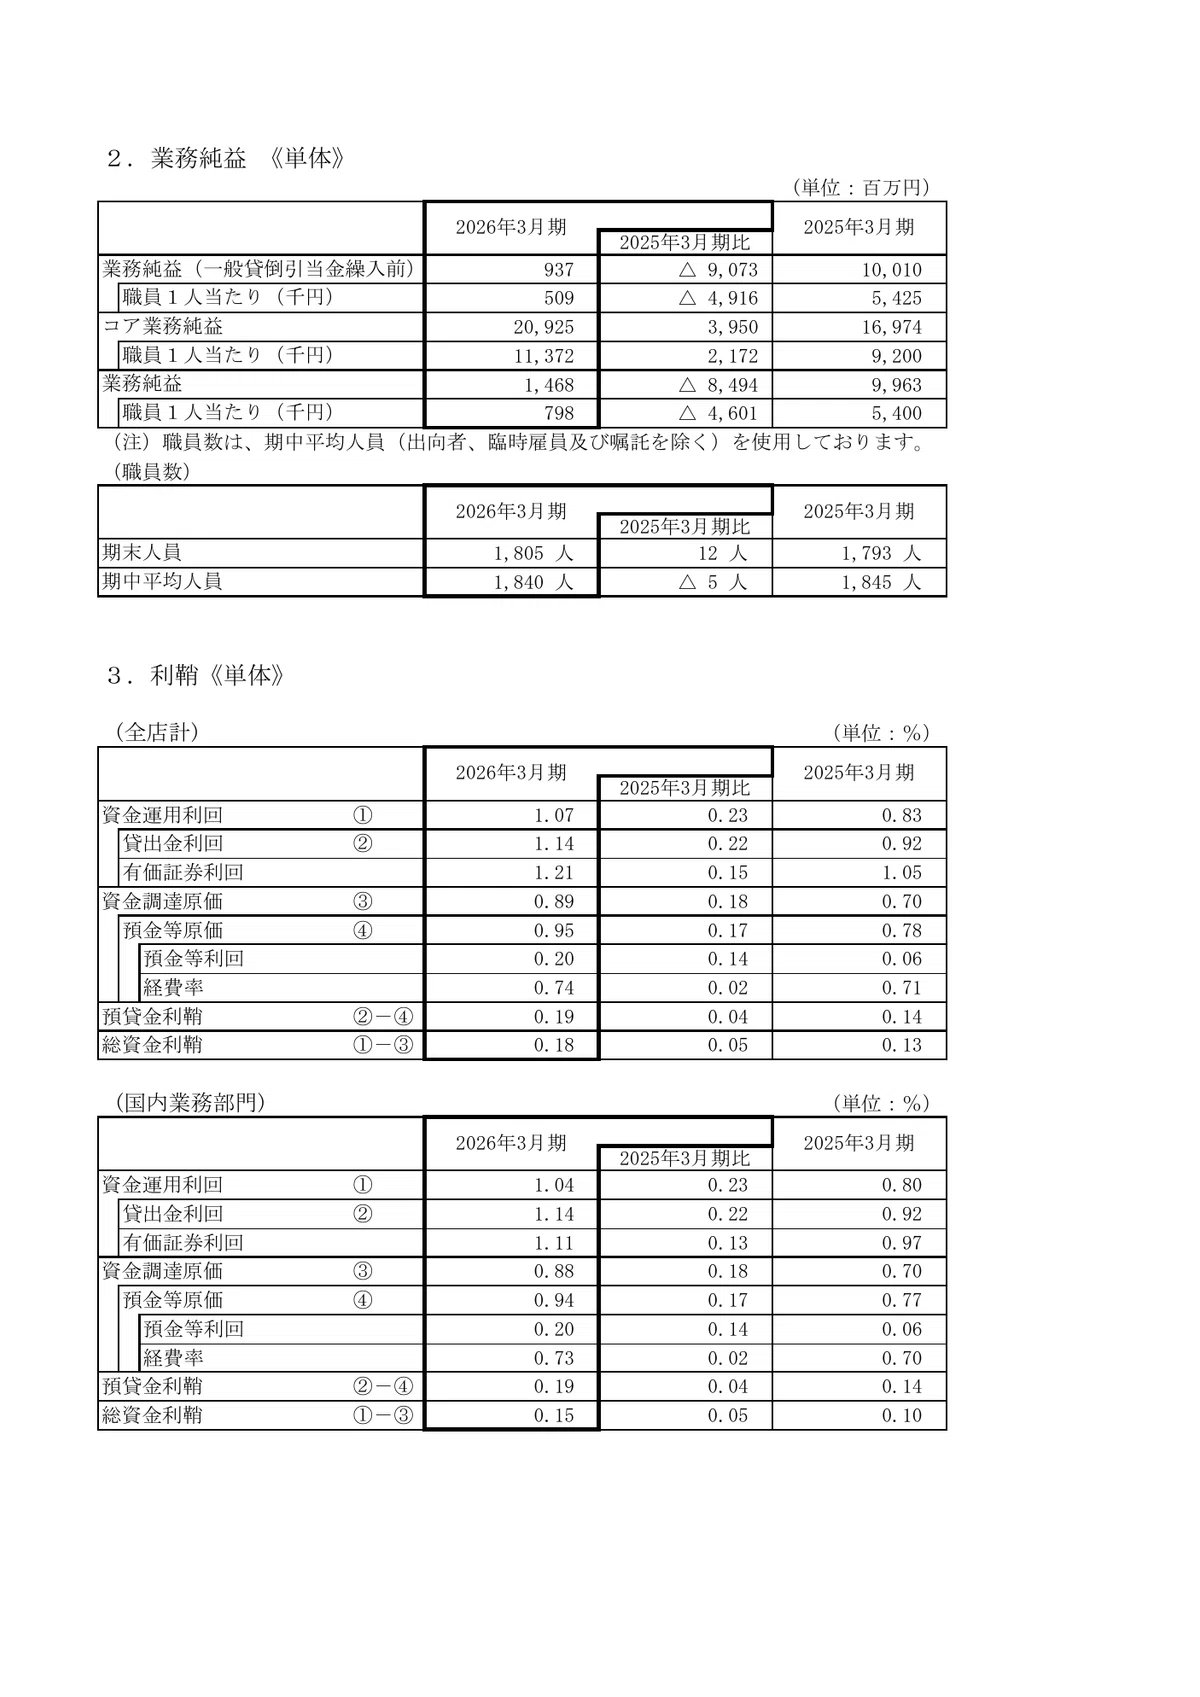
Domestic Business Segment | Fiscal Year Ending March 2026 | Fiscal Year Ending March 2025 | Loan Yield 1.14% 0.92% | Deposit etc. Yield 0.20% 0.06%
Yield is a figure indicating what percentage of interest was received (or paid) relative to the average balance. The loan yield increased by 0.22 percentage points, and the deposit etc. yield increased by 0.14 percentage points. The extent to which the rise in interest rates could be passed on to loan interest rates was greater than the extent to which deposit interest rates were raised. As a result, core net business profit increased by 23.2%, from 16,974 to 20,925.
Sold yen-denominated bonds: Losses are realized on the income statement
When interest rates rise, the price of yen-denominated bonds already held by banks falls. This is because bond interest rates are fixed at the time of issuance, so when bonds with higher interest rates appear later, older bonds with lower interest rates become relatively less attractive.
Keiyo Bank sold such yen-denominated bonds. On page 23 of the PDF, the bank explains that it “proceeded with the sale of bonds, mainly Japanese government bonds with low yields, in order to review its securities portfolio.” Selling yen-denominated bonds whose prices have fallen results in a loss on sale, but if the proceeds are used to buy bonds with higher yields, future interest income will increase. This is a decision to realize unrealized losses now in order to secure future earnings.
Almost the entire amount of the loss occurred in the domestic business segment. In the table on page 26 of the PDF, the difference between the domestic business gross profit of 40,841 and the domestic business gross profit excluding gains/losses on Japanese government bonds, etc., of 60,885 is -20,044.
The breakdown of the sales is on page 8 of the financial results presentation materials (page 29 of the PDF), titled “4. Gains/Losses on Securities (Non-consolidated).”

Gains/Losses on Japanese Government Bonds, etc. | Fiscal Year Ending March 2026 | Fiscal Year Ending March 2025 | Gain on sale 1,713 1,097 | Loss on sale 21,677 7,994 | Loss on redemption 24 66 | Total -19,987 -6,963
This -19,987 figure lowered the business gross profit through other operating income and directly reduced the net business profit. This is why net business profit fell from 9,963 in the previous fiscal year to 1,468.
To get a sense of the scale, I will compare it with core net business profit. 19,987 ÷ 20,925 = 95.5%. This means that an amount equivalent to almost the entire amount earned by the core business was used for the replacement of yen-denominated bonds.
Sold stocks: Profits are realized outside of net business profit
Meanwhile, Keiyo Bank also sold stocks it held, realizing the appreciation from the time of acquisition as profit. In the same table on page 29 of the PDF, the gain/loss on stocks, etc., is 22,879 (gain on sale 23,340, loss on sale 460).
As seen at the beginning, gains and losses on stock trading are included in “Other ordinary income/expenses” on the income statement and are not included in business gross profit or net business profit. In the table of tiered profits, it is recorded under extraordinary gains/losses (No. 25) below net business profit.
The area to the right of the dotted line in Figure 1 represents this portion. The 22.88 billion yen in stock trading gains/losses is added to the 1.47 billion yen in net business profit, and after deducting expenses such as those for non-performing loan disposal, the ordinary profit becomes 22.1 billion yen. This is 15.1 times the net business profit. The 22.88 billion yen in stock-related gains/losses is 1.14 times the -19.99 billion yen in Japanese government bond-related gains/losses, meaning the profit from sold stocks almost entirely covered the loss from sold yen-denominated bonds. The record-high net income of 15.8 billion yen is the result of following this path.
Unsold yen-denominated bonds: Unrealized losses are in net assets and are combined with unrealized gains on stocks
So, how is the decline in value of unsold yen-denominated bonds accounted for?
Among the securities held by Keiyo Bank, those classified as “other securities” are evaluated at market value at the end of each fiscal period. The valuation gain/loss table on page 29 of the PDF includes a note stating, “Regarding ‘other securities,’ since they are evaluated at market value, the difference between the balance sheet amount at the end of each fiscal period and the acquisition cost is recorded in the table above.” This difference between market value and acquisition cost represents the unrealized gain or loss.
Unrealized gains and losses do not pass through the income statement. After adjusting for tax effects, they are recorded in the net assets section of the balance sheet as “valuation difference on available-for-sale securities.” On page 15 of the PDF, in the net assets section of “4. (1) Balance Sheet” (page 13 of the table of contents for the financial results summary), this amount has increased from 5,624 at the end of the previous fiscal year to 12,312. This classification and treatment are stipulated in Accounting Standards Board of Japan (ASBJ) Statement No. 10, “Accounting Standard for Financial Instruments.”
What is important here is that this single line in net assets is the result of combining the unrealized losses on yen bonds and the unrealized gains on stocks. The valuation gain/loss table (page 29 of the PDF, “5. Valuation Gain/Loss on Securities (Non-consolidated)”) shows this broken down into stocks, bonds, and others. Figure 2 shows the net movement from the end of the previous fiscal year to the end of the current fiscal year.

The unrealized loss on yen bonds expanded by 880 million yen, from 41.79 billion yen to 42.66 billion yen. In the same year, the unrealized gain on stocks increased by 9.71 billion yen, from 54.76 billion yen to 64.47 billion yen.The expansion of the unrealized loss on yen bonds was absorbed by the increase in unrealized gains on stocks, and the total unrealized gain/loss actually more than doubled, from 8.16 billion yen to 17.92 billion yen.
The reason the expansion of the unrealized loss on yen bonds was limited to 880 million yen is that this figure is after disposing of yen bonds carrying unrealized losses by realizing a loss on sale of 21.6 billion yen this term. If they had not been sold and were held, that portion of the loss would have remained as an unrealized loss. The portion sold went to the income statement in Figure 1, and the portion not sold went to net assets in Figure 2. The same unrealized loss on yen bonds has different destinations depending on whether they were sold or not.
The unrealized gain on stocks increased due to rising stock prices, even while realizing a gain on sale of 23.3 billion yen this term. Note that Keiyo Bank’s valuation gain/loss table uses three categories: stocks, bonds, and others, and the unrealized gain/loss on stock investment trusts is not shown separately. Therefore, this article confirms the absorption relationship using the stock figures. In the “others” category, the unrealized loss shrank by 930 million yen, from 4.82 billion yen to 3.89 billion yen.
Bonds held to maturity, etc.: Unrealized losses do not appear on the balance sheet either
There is another type of unrealized loss that is recorded neither on the income statement nor in net assets. Bonds classified as “held-to-maturity” with the premise of holding them until maturity are not re-evaluated at market value, so even if their value drops, it is not reflected in the balance sheet amount (ASBJ Statement No. 10).
The first line of Keiyo Bank’s valuation gain/loss table is for this, and the unrealized loss on held-to-maturity bonds increased from 110 million yen at the end of the previous fiscal year to 2.93 billion yen. Although the scale is small, it is an unrealized loss that appears neither on the income statement nor in net assets, and can only be confirmed through disclosures like this valuation gain/loss table.
What can be read
Following Keiyo Bank’s financial results summary, the unrealized losses on yen bonds were handled in three ways.
The loss on sold yen bonds was finalized as a loss on bonds including government bonds of 19.99 billion yen on the income statement, pushing down core business profit, which is the profit from main operations, by 85%. The unrealized loss of 42.66 billion yen on unsold yen bonds (other securities) did not pass through the income statement and was combined with the unrealized gains on stocks in net assets. The unrealized loss of 2.93 billion yen on held-to-maturity bonds, etc., was not recorded in either.
And this past year, stocks supported yen bonds in both places. On the income statement, the 22.88 billion yen gain on the sale of stocks covered the loss on the sale of yen bonds. In net assets, the 9.71 billion yen increase in unrealized gains on stocks absorbed the 880 million yen expansion in unrealized losses on yen bonds.The record-high profit indicates not that the unrealized losses on yen bonds have disappeared, but that they are being absorbed by stocks.
Future clues lie in the relationship between the 42.7 billion yen in unrealized losses on yen bonds remaining in net assets and the 64.5 billion yen in unrealized gains on stocks. The former will expand if interest rates rise, and the latter will shrink if stock prices fall. The unrealized loss on yen bonds is equivalent to about two years’ worth of this term’s core business profit of 20.9 billion yen.