

After decades in which investors steadily shifted money from traditional actively managed mutual funds into low-cost index funds, the growth of active ETFs has changed the conversation. Investors no longer necessarily have to choose between the potential benefits of active security selection and the liquidity, transparency, and tax efficiency associated with ETFs. Today, billions sit in active ETFs, while new funds continue to hit the market.
However, as active ETFs grow, the realization that not every fund is a winner has begun to set in.
Recent data and market performance show that the consequences of making the wrong choice are becoming increasingly severe, and manager selection is starting to matter more.
Active Management Is Having a Moment
Passive ETFs changed the way investors of all sizes build and construct portfolios. They have democratized asset classes, allowed passive exposure to hard-to-reach markets, and done so with lower expenses and tax savings.
Now active ETFs are doing the same thing.
According to Morningstar, nearly 1,000 actively managed ETFs launched in the United States last year, up from the previous record of 584 in 2024. For comparison, only about 150 passive ETFs and 95 traditional mutual funds debuted during the year. Active ETFs attracted approximately $475 billion of net inflows in 2025, representing roughly one-third of all ETF inflows.
Globally, active ETF assets reached approximately $1.6 trillion by the end of 2025, after growing at a compound annual rate of roughly 47% since 2020. By mid-2026, actively managed ETFs actually outnumbered passive ETFs in the United States by fund count.
Investors now have active ETFs covering everything from large-cap stocks and small companies to international markets, bonds, options strategies, and alternatives.
That is welcome news for investors looking to generate market-beating returns.
Not All Active Management Is Winning
The industry’s rapid growth creates an important problem. Active management rests on a simple proposition: a manager can deviate from an index when research suggests a better opportunity exists, and that flexibility can be enormously valuable.
It can also go badly wrong, and new research from State Street shows just how badly.
SSGA examined U.S. large-cap active managers benchmarked against the S&P 500 and found that the gap between the strongest and weakest managers has widened dramatically.
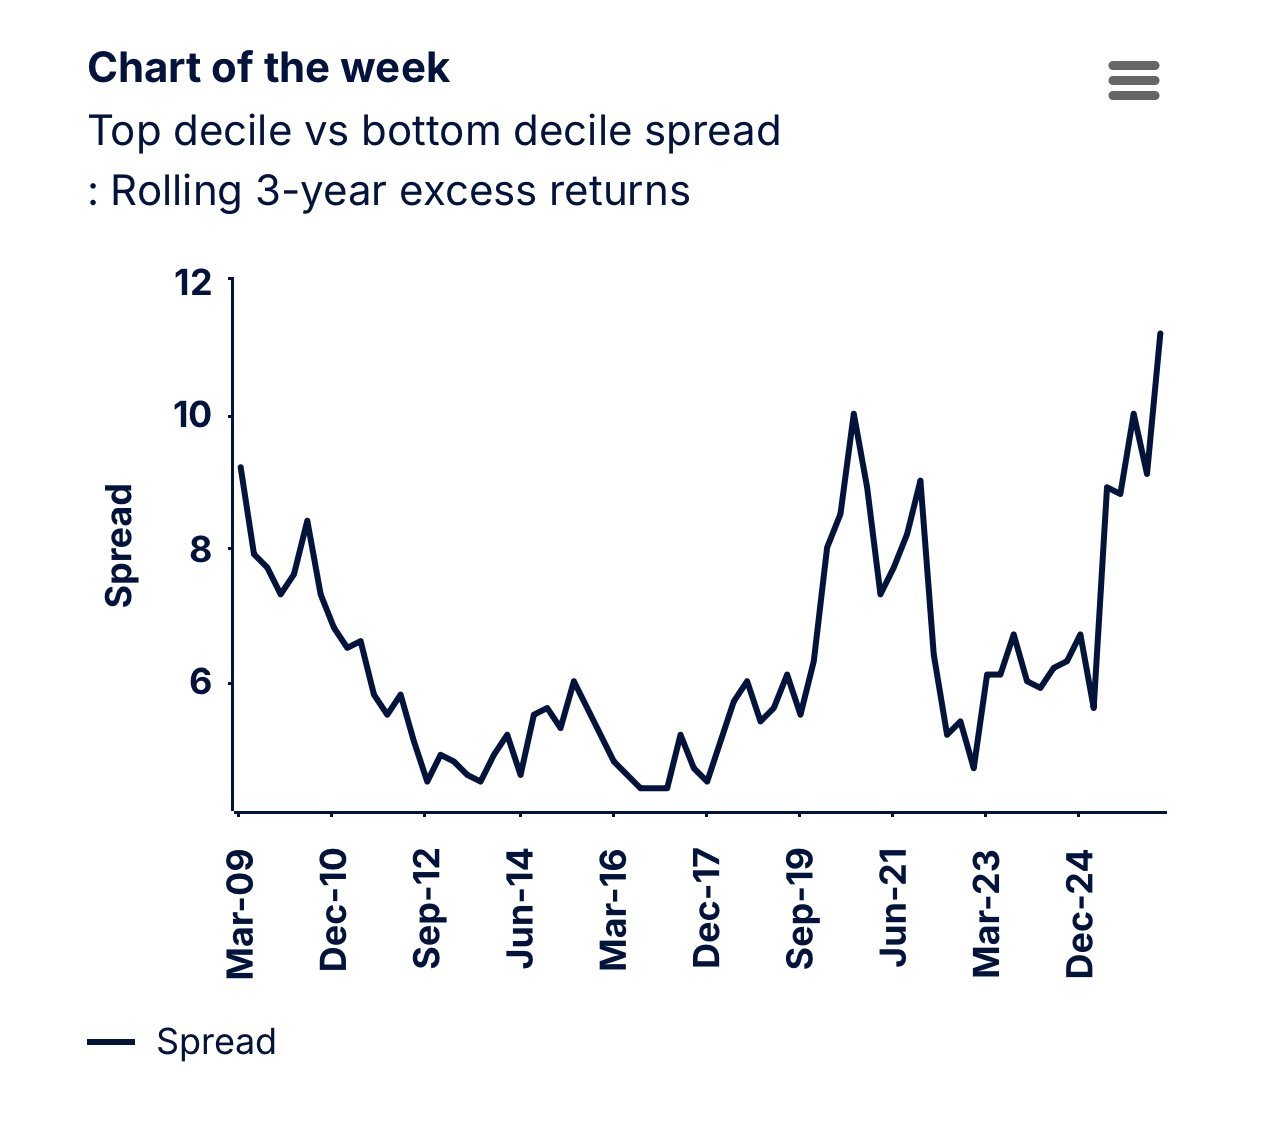
The spread between the top and bottom deciles of active managers’ rolling three-year excess returns reached 15.6 percentage points through the second quarter of 2026, placing the difference near its highest level in two decades.
This chart highlights the spread between top and bottom managers, and as you can see, it is growing.
Source: State Street Global
More interesting in SSGA’s study is why the gap has grown.
It is not primarily because the best active managers have suddenly become dramatically better. Instead, the weakest managers have become considerably worse.
Over the past 20 years, the average rolling three-year excess return for a bottom-decile manager was approximately negative 3.9%. For the three-year period ending in the second quarter of 2026, bottom-decile managers underperformed by 8.3%.
In State Street’s latest three-year portfolio comparison, the differences were even more striking. Top-decile managers generated an average excess return of 5.43%, while bottom-decile managers lagged by 10.15%.
The reason is also telling: active decision-making drives the disparity in returns, making clear that for investors, “active” is not a strategy by itself.
The dispersion extends beyond portfolio returns to the active ETF industry itself. Although active ETFs now outnumber passive ETFs by fund count, investor assets remain highly concentrated in a relatively small number of successful strategies.
How to Choose an Active Manager
The widening gap between active winners and losers makes manager selection considerably more important.
Investors should start with process rather than recent performance.
A manager who happened to own several hot stocks last year is not necessarily skilled. Investors should understand how securities are selected, what causes the manager to buy or sell, how much freedom the portfolio has to deviate from its benchmark, and whether that process has remained consistent across different market environments.
Portfolio construction matters just as much as stock selection.
State Street’s research demonstrates why. Bottom-decile managers were not necessarily avoiding good companies entirely. In many cases, they simply didn’t own enough of the market’s strongest businesses for those positions to meaningfully help returns.
Investors need to examine a portfolio’s holdings and strategy carefully before making a buy decision.
Active Large-Cap Equity ETFs
These active ETFs were selected based on their lower concentration risk relative to the broader S&P 500 and are sorted by year-to-date total return, ranging from 16% to 51%. They carry expenses between 0.15% and 0.59%, AUM between $760M and $21B, and current yields between 0% and 1.45%.
| Ticker | Name | AUM | YTD Total Ret (%) | Yield (%) | Exp Ratio | Security Type | Actively Managed? |
|---|---|---|---|---|---|---|---|
| FBCG | Fidelity Blue Chip Growth ETF | $764M | 50.5% | 0% | 0.59% | ETF | Yes |
| CGGR | Capital Group Growth ETF | $2.84B | 34.5% | 0.38% | 0.39% | ETF | Yes |
| CGUS | Capital Group Core Equity ETF | $1.32B | 22% | 1.24% | 0.33% | ETF | Yes |
| DFAC | Dimensional U.S. Core Equity 2 ETF | $20.45B | 16% | 1.34% | 0.17% | ETF | Yes |
| AVUS | Avantis U.S. Equity ETF | $4.53B | 16% | 1.45% | 0.15% | ETF | Yes |
As active ETFs continue taking market share, investors will have more opportunities than ever to incorporate professional security selection into their portfolios.
The next phase of the active ETF revolution may be less about whether active management wins and more about which active managers do.
Bottom Line
Investors have more active ETFs to choose from than ever, but the widening gap between the best and worst managers shows that simply choosing an active strategy is not enough.