
India’s savings story has changed sharply over the past decade. While bank deposits remain the largest single destination, retirement-oriented and market-linked products together now account for a bigger share of household financial savings.
According to Franklin Templeton India Mutual Fund’s report titled “Financialization of Savings in India – From Safety to Scale”, India’s financialisation journey is improving but remains in its early stages.
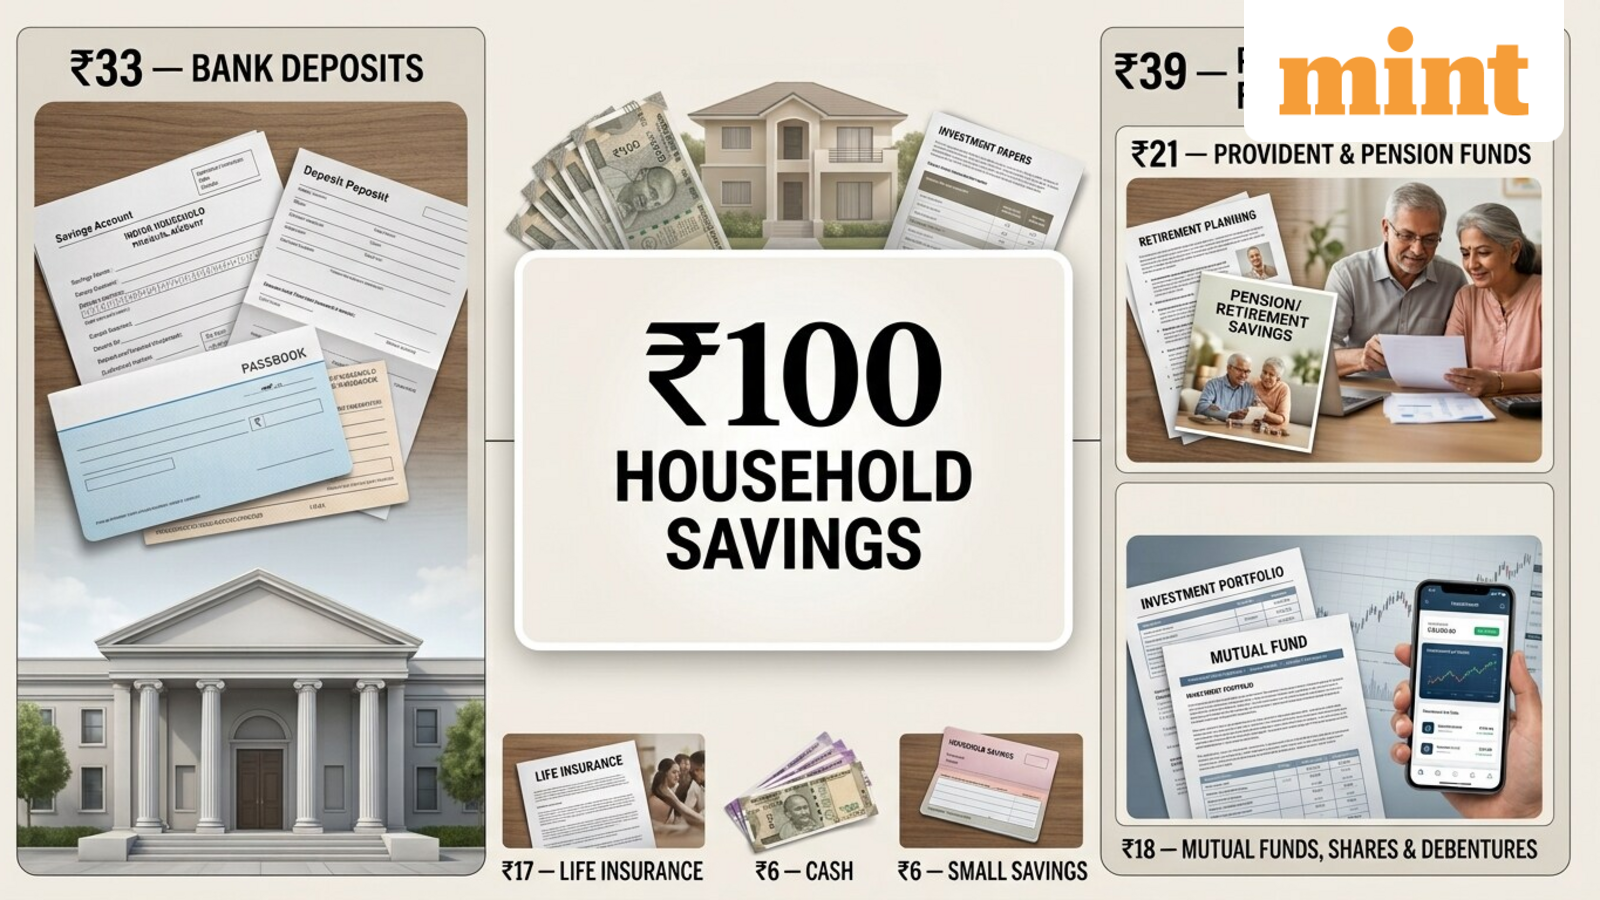
What happened to every ₹100 of India’s household financial savings?
Bank deposits accounted for 52% of gross financial savings during FY71-80 (1971-72 to 1979-80). By FY25, their share had fallen to 33%.
Meanwhile, mutual funds, shares and debentures rose from 0% to 18%. Their share increased from 4% in FY21 to 11% in FY24 and 18% in FY25. In FY25, this market-linked category also overtook life insurance at 17%.
Provident and pension funds remained relatively stable, with their share rising from 19% in FY71-80 to 21% in FY25.
Together, provident and pension funds, mutual funds, shares and debentures now account for 39% of household financial savings.
This means that out of every ₹100 of household savings, ₹33 goes to bank deposits, while ₹39 goes to provident and pension funds, mutual funds, shares and debentures.
“India’s savings landscape is being redrawn as households rebalance toward higher-return instruments and accept greater market-linked risk,” according to the report.
Does India still have a long way to go?
Yes. About 65% of India’s population is below 35, with a median age of around 28. “Industry expectations suggest gross financial savings could more than triple over the next decade as digital rails lower entry barriers”, the report noted.
Between March 2020 and March 2025, managed investments grew at a CAGR of about 17.5%, compared with 11.7% for bank deposits.
The difference between the two categories narrowed from nearly ₹32 lakh crore to ₹7 lakh crore, reflecting broader household participation across financial instruments.
Yet as of May 2026, deposits still represented 54% of Indian household assets, second only to China’s 55%, while securities accounted for just 12%.
Why does India still look different from developed economies?
Indian households remain heavily invested in physical assets. In FY25, an estimated 68% of household wealth was in physical assets, including 10-12% in gold and 57-60% in real estate. This share could moderate to 58-64% as financial holdings increase.
Equities have already risen 2.3 times as a share of household assets, from 2.9% in March 2015 to 6.6% in March 2025.
As of June 2026, India’s equity share was just 7% as compared to 26% in the US and 17% in Taiwan. The report noted that “there remains substantial headroom for further growth”.
How quickly are mutual funds growing?
Mutual fund AUM rose from ₹35.32 lakh crore in July 2021 to ₹85.76 lakh crore in July 2026, a CAGR of about 19%, driven by retail participation, SIP adoption and younger investors’ shift towards market-linked savings.
Despite strong growth, India remains under-penetrated by global standards. India’s mutual fund industry’s AUM-to-GDP ratio was 21% in FY26, remaining below developed-market levels.
What is driving the shift?
“India’s financialization is different because it is being built on public digital infrastructure at population scale,” the report explained.
The JAM (Jan Dhan, Aadhaar, Mobile) trinity, Aadhaar-enabled e-KYC, UPI, and the wider consent-based data architecture around Account Aggregator have lowered the cost of discovery, onboarding, and servicing.
Financial products that once required branch infrastructure, paperwork, and people to hand-hold can now be originated and serviced digitally, extending formal investing well beyond metros.
Rising incomes are increasing risk-taking ability, while more than 80% of the workforce, including agricultural workers, remains outside the formal sector.
What does this mean for investors?
“Households are building portfolios. What is changing is not just product adoption but financial intent,” the report mentioned.
Indian households are moving from a savings-first mindset to a portfolio mindset: emergency money stays liquid, protection is increasingly formalised, and long-term wealth is being routed into market-linked instruments.
The report notes that mutual funds, pensions, AIFs, PMS, insurance, direct equities and digital wealth platforms are all participating in the same structural shift. Households are no longer investing in a one-size-fits-all mode but are becoming more purpose-driven, investing for “liquidity, protection, growth and retirement.”
As household financial needs become more differentiated, the report says the role of distribution partners may evolve beyond facilitating transactions to supporting investor awareness and informed decision-making across these needs.
Disclaimer: This is purely for educational/informational purposes and should not be taken as any sort of investment advice. Always consult a SEBI-registered advisor before making any investment decisions.