
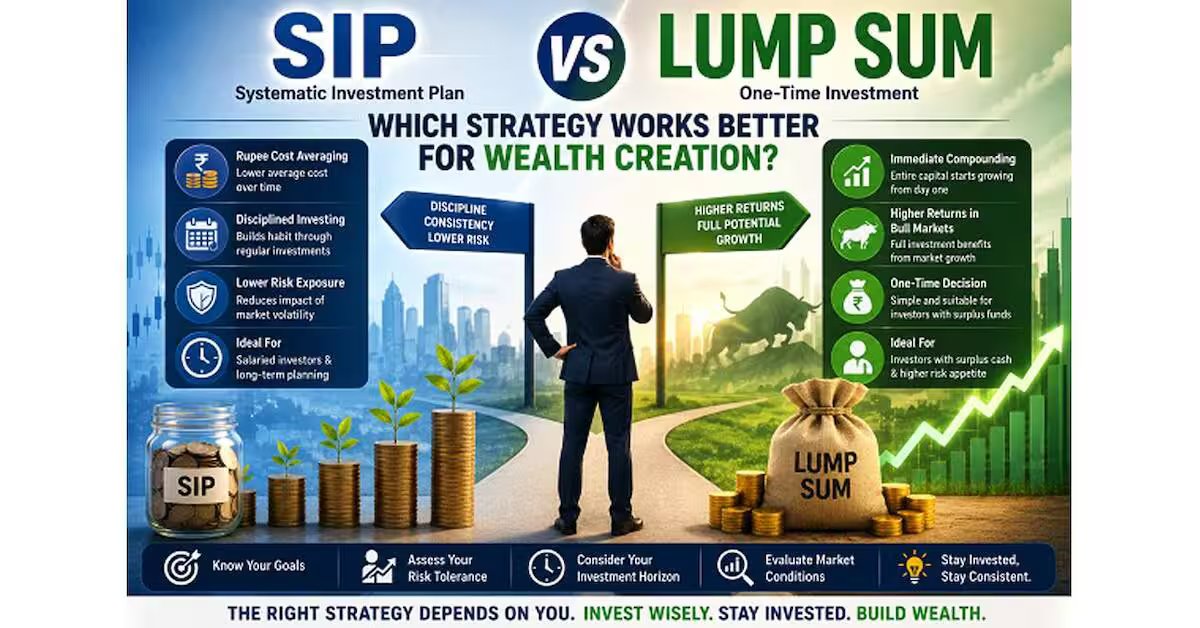
The BSE barometer Sensex is currently about 14 per cent below its record of about 86,000 points hit in late 2025 and has moved in a range of roughly 71,600 to 74,700 through October. For investors with a lump sum to deploy, such as a bonus or a matured fixed deposit, the question is whether to invest it all now or stagger it.
Idle cash is uncommon to begin with. Rishit Shah, QPFP, says investors whose financial planning is in order seldom have extra money lying around. Surplus usually arrives with a hike or a bonus.
The math vs the risk
On average, investing a lump sum has emerged as a better approach.
A Vanguard study from 2023 found a lump sum beat a three-month staggered plan about 68 per cent of the time. It used MSCI World Index data from 1976 to 2022 and compared wealth after one year. Equities tend to rise over time, so cash waiting on the sidelines costs returns.
The gap shows up when markets fall. In the worst 5 per cent of one-year periods, ₹1 lakh invested at once in an all-equity portfolio fell to about ₹83,000, while the same money staggered over three months fell to about ₹86,000.
Sensex data
The table shows what a ₹5,000 monthly SIP in the Sensex would be worth today, against the same total invested as a lump sum on day one.
| Period | Total invested | SIP value | Lumpsum value |
| 1 year | ₹60,000 | ₹56,358 | ₹52,259 |
| 5 years | ₹3,00,000 | ₹3,20,892 | ₹3,68,642 |
| 10 years | ₹6,00,000 | ₹9,26,243 | ₹15,82,800 |
| 20 years | ₹12,00,000 | ₹34,10,833 | ₹68,53,098 |
Lumpsum means the whole amount invested on day one. The SIP spreads the same total over monthly instalments. Source: analysis of BSE Sensex daily closing values to October 21, 2026. Sensex price index, which excludes dividends. Figures are before tax.
What it means: over the past year, the SIP lost less because more units were allocated. Over five years and longer, the lump sum finished well ahead, because all of its money was invested from the start in this example. A lump sum does better when markets keep rising, while a SIP, or staggering a lump sum, softens the blow when they fall.
What mutual fund distributors say: Stagger surplus capital
“If you have a long investment horizon, a lump sum investment in equities increases your market exposure, but exposes you to potential losses if the market corrects immediately. Investing in staggered intervals over 3 to 6 months can reduce timing and behavioural risks,” says Rajesh Minocha, CFP, Founder & CEO of Financial Radiance.
He says a SIP or Systematic Transfer Plan (STP) can work well in volatile, sideways markets, especially when prices dip. But a sideways market is identifiable only in hindsight, he adds, and a lump sum can do better if prices rise sharply or if it lands at the bottom. Nobody knows the bottom until afterwards, so he advises against sitting in cash indefinitely.
Shah says a sideways market helps SIP investors, who buy at varying prices. For someone with no running SIP, he suggests spreading a lump sum over six to ten months, which he considers enough for most people. He says getting the timing right on a lump sum is difficult for general investors, and the final call depends on risk appetite and how comfortable the investor is with a drawdown.
The middle path: an STP
For a fresh lump sum, distributors commonly suggest an STP. The entire amount goes into a liquid or debt fund, which has returned roughly 6 to 6.5 per cent over the past year. Fixed monthly instalments are then moved into an equity fund over 3 to 10 months.
For example, take ₹12 lakh in a liquid fund, with ₹2 lakh moved into equity each month for six months, starting on day one. At about 6 per cent, the money waiting in the liquid fund would earn roughly ₹15,000 over the period, before tax.
Also, each transfer is a redemption from the debt fund and a taxable event. Gains on debt funds bought on or after April 1, 2023 are taxed at the investor’s income slab rate.
Disclaimer: Views and outlook in this report belong to the brokerages and analysts cited. They do not reflect the views of Business Standard. Readers are advised to exercise discretion.