

“After FIRE, I want to receive a stable monthly income just from corporate bond interest, like a bank deposit, without worrying about stock price fluctuations.”
This is one of the most ideal life plans.
However, corporate bonds have a fatal weakness: they are “fixed-rate (the payout amount does not change).”
For example, suppose you created a portfolio that pays 2 million yen in annual interest (about 167,000 yen per month) at a 4% net yield. The first year provides sufficient living expenses, but if inflation (rising prices) progresses at a pace of 2% per year, 10 years later, the real purchasing power will drop to about 82%, 20 years later, it will drop to about 67% (equivalent to 110,000 yen today).
So, how can you take advantage of the benefits of corporate bonds—”low price volatility and regular interest payments”—while also dealing with inflation?
In this article, I will explain the specific prescription in three steps.
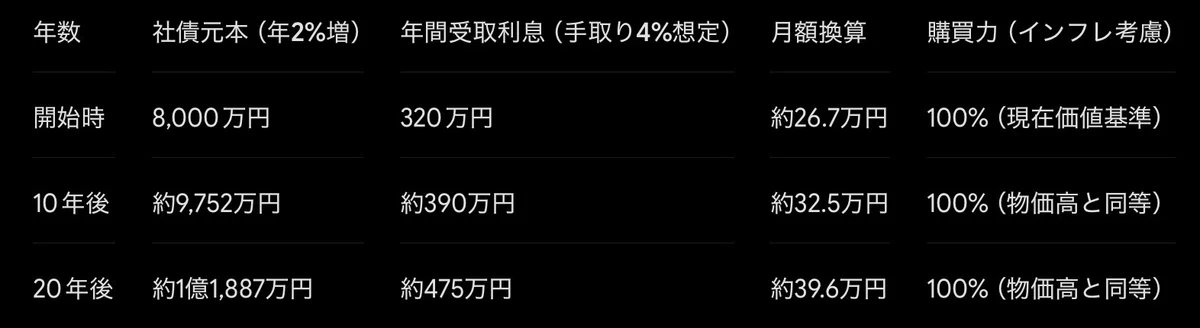
Approach 1: Increase the corporate bond principal by 2% annually through “profit replenishment” from growth assets.
The most classic and effective method is a hybrid strategy where you “do not put everything into corporate bonds, but keep about 20% in growth assets (such as the S&P 500 or global stocks).”
Mechanism
Asset Allocation: 80% Corporate Bonds / 20% Stocks
Investment Rules:
1. Receive all corporate bond interest as daily living expenses.
2. Use a portion of the annual returns (capital gains and dividends) obtained from stocks to purchase additional corporate bonds (add to the principal) in line with the inflation rate.
By using the growth power of stocks for “inflation adjustment of the corporate bond principal,” you can raise the actual amount of living expenses received by 2% each year, maintaining purchasing power into the future.
Approach 2: Capture the benefits of rising interest rates with a “bond ladder (maturity diversification).”
In an inflationary phase, market interest rates tend to rise due to monetary tightening (interest rate hikes) by central banks.
However, if you buy long-term fixed-yield corporate bonds, such as 10-year bonds, all at once, you will not be able to benefit even if interest rates rise, and you will instead face the risk of bond prices falling.
Therefore, I recommend a “bond ladder strategy.”
[Image of a Bond Ladder]
1-year maturity bond: [10 million yen] ───→ Reinvest in high-interest corporate bonds (5-year, etc.) at that time upon maturity
2-year maturity bond: [10 million yen] ───→ Reinvest in high-interest corporate bonds at that time upon maturity
3-year maturity bond: [10 million yen] ───→ Reinvest in high-interest corporate bonds at that time upon maturity
4-year maturity bond: [10 million yen] ───→ Reinvest in high-interest corporate bonds at that time upon maturity
5-year maturity bond: [10 million yen] ───→ Reinvest in high-interest corporate bonds at that time upon maturity
Benefits of building a ladder
1. Can respond to inflation and rising interest rates: Since a portion matures every year, if interest rates have risen, you can switch to new corporate bonds with higher rates.
2. Neutralization of price decline risk: Since you assume holding until maturity, you do not need to worry about the ups and downs of bond prices in the meantime.
3. Ensuring liquidity: Since the principal is returned every year, you can flexibly respond to unexpected expenses.
Approach 3: “Currency and Type Diversification” that is not biased only toward domestic corporate bonds.
If you try to achieve a “4% net yield” using only domestic corporate bonds (yen-denominated), you will tend to lean toward subordinated bonds or credit products with low credit ratings (such as high-yield bonds), increasing default risk.
To strengthen your resistance to inflation, the balance of the following three is essential:
1. US dollar-denominated corporate bonds (senior bonds of blue-chip companies)
It is easy to aim for a yield of around 4-5% on corporate bonds of blue-chip US companies (investment-grade rating A to BBB or higher).
Currency diversification (holding dollars) itself acts as a natural hedge against future yen depreciation and inflation.
2. Floating-rate notes (domestic/overseas)
Incorporate bonds with a mechanism where coupons (interest received) are revised in conjunction with inflation and rising interest rates.
3. Inflation-indexed bonds (TIPS, etc.)
Incorporate some bond ETFs where the principal increases in line with the inflation rate (CPI) to strengthen inflation resistance.
Summary: A checklist to evolve corporate bonds into an “inflation-adjusted pension.”
Corporate bonds are excellent as a “stable source of regular income after retirement,” but they are also “assets whose value will definitely be eroded by inflation if left alone.”
[ ] Do not put everything into corporate bonds; have you left 15 to 20% in growth assets such as index stocks?
[ ] Do you have a rule to replenish the returns from growth assets to “increase the corporate bond principal (target of 2% per year)”?
[ ] Is it a “ladder structure” with maturities spread out in 1-year to several-year increments?
[ ] In preparation for yen depreciation and inflation, have you incorporated high-quality foreign currency-denominated corporate bonds or currency diversification?
By designing with these in mind, I have considered ways to complete a “solid personal pension that allows you to maintain your standard of living even if prices rise,” without being afraid of stock market volatility.
Currently, the proportion of stock investment is very high, but I suppose I will use a method like this at some point…
Part 1 is here ↓