
Early redemptions of retail government bonds exceeded 200 billion won ($134 million) in the first half of this year, new data show.
The surge is largely attributed to a sharp increase in the bonus interest rate on newly issued bonds, which has given existing holders a financial incentive to redeem their lower-rate bonds early and reinvest in the higher-yielding new issues.
According to a fiscal-year 2025 settlement analysis published recently by the National Assembly Budget Office, early redemptions of retail government bonds totaled 211.1 billion won in the January–June period.
The retail government bond program was introduced in June 2024 as a savings-type instrument designed to help ordinary citizens build long-term assets and broaden the government bond investor base.
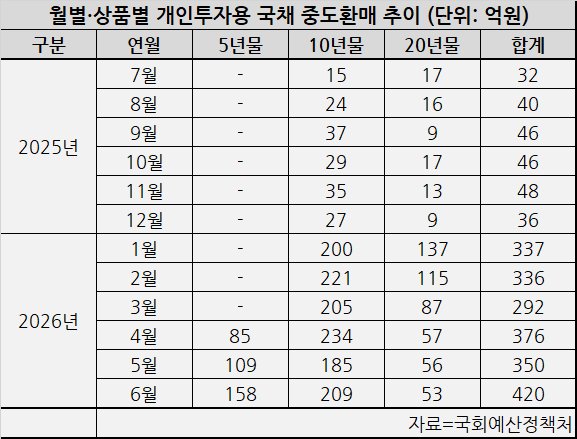
Monthly redemption figures were 33.7 billion won in January, 33.6 billion won in February, 29.2 billion won in March, 37.6 billion won in April, 35 billion won in May and 42 billion won in June. January’s redemptions alone surpassed the 24.8 billion won recorded for the entire second half of last year, and June set a new monthly record.
April was particularly notable, as five-year bonds became eligible for early redemption for the first time that month. Of the 37.6 billion won redeemed in April, 8.5 billion won came from five-year bonds — representing 10.7 percent of the 79 billion won in five-year bonds issued in March last year.
The budget office identified the sharp adjustment in bonus interest rates as the primary driver of the redemption surge.
During the second half of last year, even as market interest rates rose, the government made only minor tweaks to the bonus rate, keeping the combined rates on 10-year and 20-year bonds at roughly 3.385 percent and 3.500 percent, respectively. Starting with bonds issued in January this year, under a plan to revitalize the retail bond program, the government raised the combined rate on 10-year bonds to 4.410 percent and on 20-year bonds to 4.615 percent — increases of more than 1 percentage point each.
Retail government bonds held to maturity earn annually compounded interest on the bonus rate and qualify for a separate, lower tax rate on interest income. The budget office said the gap in combined rates has a significant impact on actual returns at maturity, creating an incentive for holders of older, lower-rate bonds to redeem early and switch to newly issued bonds. It added that this pattern of redemption and reinvestment was entirely foreseeable when the bonus rate was sharply raised.
The government raised the bonus rate to stimulate demand for retail bonds. Issuance last year reached 1.21 trillion won, falling short of the annual target of 1.3 trillion won. Subscription shortfalls persisted, particularly for 10-year and 20-year bonds, which carry a longer holding commitment, and from October last year even five-year bonds began to see undersubscription as funds flowed into the stock market.
The budget office said that as long as the current bonus rate structure remains disconnected from market rate movements, pressure for early redemptions on previously issued bonds is likely to persist throughout this year.
It also warned that redemption volumes could exceed current levels in the second half of this year, as bonds issued in the first half of last year become eligible for early redemption one by one. The office said some of the new retail bond issuance demand this year also appears to reflect replacement demand driven by early redemptions of bonds issued in 2025.
The government has characterized the trend as a portfolio rebalancing process by early investors, but the budget office said the rise in early redemptions shortly after issuance runs counter to the program’s original purpose. Because retail government bonds are designed to encourage long-term holding through benefits such as separate taxation and compound interest, a spike in short-term redemptions conflicts with the program’s goal of supporting long-term asset accumulation, it said.
In response, the budget office recommended that the government strengthen the link between bonus rate adjustments and market interest rates, and establish and publish clear, rational criteria for the size of any adjustments so that investors can better anticipate future rate changes.
Under the current structure, the office said, investors’ purchase decisions may be driven more by the government’s bonus rate policy direction than by their own outlook on market rates — suggesting that the bonus rate has effectively functioned as a policy variable tied to issuance performance and fund costs.
The budget office also said it found no evidence that other major economies operating programs similar to Korea’s retail bond scheme — including the United States and the United Kingdom — have adopted an artificial bonus rate system of this kind.
It further recommended a review of whether it remains appropriate for the Public Fund Management Fund to bear the full cost of the bonus rate, given that the fund already pays a higher interest rate than on ordinary government bonds to issue retail bonds — a structure that, if sustained, raises questions about its fiscal justification.
y2k@heraldcorp.com
This content was produced with the assistance of AI translation services.