

What exactly are corporate bonds for individuals?
—Why the ‘plain character of the bond world’ is suddenly becoming popular due to rising long-term interest rates—
Introduction—Stocks aren’t the only way to invest
When people think of prominent figures in the investment world, they think of stocks.
If stock prices soar,
“Whoa! It hit the daily limit high!”
If they crash,
“I shouldn’t have looked at the chart…”
Your emotions become a rollercoaster.
Sitting quietly on the sidelines is the corporate bond.
Corporate bond: “I will pay interest every six months. I will return the principal when it matures.”
Investor: “…That’s plain.”
However, the situation changes when interest rates rise.
Corporate bond: “This time, the interest rate is a bit higher.”
Investor: “Huh?”
Corporate bond: “The interest rate has gone up.”
Investor: “You… were you always this attractive?”
Thus, in a world with interest rates, corporate bonds for individuals begin to increase their presence.
In this article, we will look at everything from “What exactly is a corporate bond?” to its relationship with rising long-term interest rates, the appeal of corporate bonds for individuals, and points to keep in mind when purchasing them.
1. What exactly is a corporate bond?
Simply put, a corporate bond is
a bond issued by a company to borrow money from investors
.
Companies need money to conduct their business.
They want to build a factory.
They want to build a data center.
They want to develop a new product.
They want to expand overseas.
They want to make the chairs in the president’s office out of gold.
The last one might get them scolded at a shareholders’ meeting, but regardless, companies need funds.
Therefore, companies sometimes raise funds directly from investors by issuing corporate bonds, rather than just borrowing from banks. The Japan Securities Dealers Association also defines corporate bonds as bonds issued by companies to raise business funds for purposes such as capital investment.
In other words, the relationship is
Investor → Money → Company
Company → Interest + Principal at Maturity → Investor
.
In the case of a bank deposit, you deposit money with a bank, but with a corporate bond, it is effectively saying,
“Company, please use this 1 million yen for a while.”
becomes the case.
Company: “Thanks! I’ll pay you back with interest!”
Investor: “I’m counting on you!”
It is the financial version of “Make sure you return the eraser I lent you.”
2. What is the difference between stocks and corporate bonds?
This is very important.
When you buy stocks, you become a shareholder of that company.
On the other hand, when you buy corporate bonds, you become a creditor who is lending money to that company.
Therefore, stocks basically do not have a maturity date.
However, general corporate bonds have,
“We will return the principal on Month/Day/Year”
a redemption date.
Furthermore, you receive interest based on a set interest rate.
Stock: “If the company grows, the stock price might double!”
Corporate Bond: “I basically get a set interest rate.”
Stock: “Let’s dream big!”
Corporate Bond: “I look at the repayment schedule.”
Their personalities are too different.
3. So, what are “individual corporate bonds”?
Many regular corporate bonds are intended for institutional investors.
Therefore,
“Let’s make them easier for ordinary company employees and individual investors to buy”
is the reason why purchase units were made smaller, which are individual corporate bonds.
The Japan Securities Dealers Association explains that individual corporate bonds are bonds issued with a minimum purchase unit reduced to around 1 million yen so that individual investors can easily purchase them.
In short,
Institutional investor: “100 million yen!”
Individual investor: “Please don’t say such an amount as if it were supermarket loyalty points.”
It is a product that solves that problem.
However, the purchase unit and conditions vary depending on the issue.
4. Why do corporate bonds attract attention when long-term interest rates rise?
This is the main topic of this section.
Corporate bond yields are not unrelated to general interest rates.
When a company issues corporate bonds, investors compare them with other financial products such as government bonds.
For example, in a world where government bond yields are low,
Company: “Our corporate bond offers 1% per year.”
Investor: “Oh, that’s not bad.”
Suppose that was the case.
However, if long-term interest rates rise and you can get higher yields than before even with highly safe government bonds,
Company: “We’d like to offer 1% per year again this time!”
Investor: “No, no, no.”
That is what happens.
Since you are going out of your way to take on a company’s credit risk, you want a yield that justifies it.
Therefore, in a phase where market interest rates are rising, upward pressure is easily applied to the interest rates and yields of newly issued corporate bonds as well.
Long-term interest rate: “I am rising.”
Government bond yields are rising.
The corporate bond market says, ‘We have to reconsider our terms, or we won’t be able to sell them!’
Companies say, ‘Our funding costs are skyrocketing!’
That is how it goes.
5. However, ‘rising interest rates’ does not mean ‘everyone holding corporate bonds is happy’.
Here is one of the biggest trick questions in the bond world.
Generally,
when interest rates rise, the price of bonds already issued falls.
Conversely,
when interest rates fall, the price of existing bonds rises.
The Japan Securities Dealers Association also clearly explains this relationship.
Why is that?
Suppose the interest rate on a corporate bond you bought a long time ago was 1% per year.
Then, interest rates rise, and similar newly issued corporate bonds offer 2% per year.
New bond: ‘It’s 2%!’
Old bond: ‘It’s 1%!’
Investor: ‘…I’ll take the 2%.’
Old bond: ‘Wait!’
Therefore, to sell an old corporate bond on the market, you have to lower the price, or it will be difficult to find a buyer.
This is why,
Rising interest rates → Falling bond prices
is the basic mechanism.
6. So what happens if you hold it until maturity?
This is the key point to understanding corporate bond investment.
In the case of standard fixed-rate corporate bonds, even if the market price drops during the term, as long as the issuing company can make repayments properly, holding it until maturity means you will receive redemption under the promised terms.
In other words, even if in the middle,
1 million yen
↓
market price 950,000 yen
it becomes,
Investor: “Oh no! 50,000 yen has disappeared!”
Corporate bond: “You haven’t sold it yet, have you?”
such cases exist.
The Japan Securities Dealers Association also warns that while the principal is returned in principle if held until maturity (excluding cases like bankruptcy), selling before maturity involves selling at market price, which may result in a loss.
Therefore, with corporate bonds,
“whether you care about interim price fluctuations or whether you hold until maturity”
becomes extremely important.
7. Appeal of corporate bonds for individuals (1) Interest is easy to predict
With ordinary fixed-rate corporate bonds, the interest rate and maturity are determined at the time of purchase.
Therefore,
“If I hold this corporate bond until maturity, I can receive about this much interest”
makes it easy to plan.
In the case of stocks,
Investor: “What will the stock price be next year?”
Market: “Who knows?”
That is how it goes.
With corporate bonds,
“This is the interest payment date”
“This is the redemption date”
The schedule is relatively clear.
Being able to easily plan your asset management is a major attraction.
8. Attraction 2: In a rising interest rate environment, you can expect improved terms for newly issued bonds
In an era where low interest rates continued for a long time,
Investor: “Even if I buy corporate bonds, the interest is…”
This was the situation.
However, if market interest rates rise, higher yields are more likely to be required for newly issued corporate bonds.
In other words, in a world with interest rates,
“I want to earn interest income without aiming for as much price appreciation as stocks”
For people like this, the options for corporate bonds will look more attractive than before.
The bond world has woken up from a long hibernation.
“Good morning. There is interest.”
9. Attraction 3: You can hold assets different from stocks
If you put all your assets into stocks,
Stock market: “I’m going to crash.”
Assets: “We’re all going down together!”
This is a possibility.
Therefore, there is a concept of combining assets with different characteristics, such as deposits, government bonds, corporate bonds, and stocks.
Unlike stocks, corporate bonds are basically debt instruments that pay interest and principal from a company.
Therefore, they serve to increase the options for asset management.
However,
“Buying corporate bonds is absolutely safe!”
This is not the case.
From here on, we will cover the precautions.
10. Precaution 1: The biggest problem—the company might not be able to pay you back
The biggest risk of corporate bonds is credit risk.
If the issuing company’s business deteriorates and it goes bankrupt, there is a possibility that interest and principal will not be paid as scheduled.
This is where bank deposits and corporate bonds differ significantly.
Corporate bonds are not bank deposits.
Therefore,
“It’s a famous company, so it’s 100% safe”
is not necessarily true.
When purchasing,
It is important to check the issuing company’s performance, financial status, credit rating, and business details
is important.
Especially when you see a corporate bond with a very high yield,
Investor: “The interest rate is so high! What a god-tier product!”
jumping into it is dangerous.
This is because the high yield may reflect the credit risk of the issuing company.
In the financial world, it is often said that
there is a reason for high returns.
It is the same as how you should check the reason for a free extra-large bowl of ramen.
11. Caution Point 2: Possibility of loss if sold midway
“The maturity is in 5 years, but I need money next year!”
If this happens, you may need to sell the corporate bond midway.
However, there is no guarantee that it can be sold at the same price as the purchase price at that time.
Especially if interest rates have risen, the price of existing bonds tends to fall.
Furthermore, some corporate bonds are not traded as actively as stocks, so there is also liquidity risk where you cannot sell at your desired price immediately. Depending on market conditions and the credit status of the issuing company, you may only be able to sell at a significantly lower price, or it may not be easy to find a buyer.
Therefore,
putting all the money you plan to use within a few years into corporate bonds
requires careful consideration.
12. Caution Point 3: Do not choose based solely on the “interest rate”
When choosing corporate bonds,
Company A 1.5%
Company B 2.0%
Company C 4.0%
if they are listed like this,
“Company C!”
is what you might think.
However, what is important is,
why does Company C have to pay 4% to raise funds?
is the perspective to have.
What you want to check is the creditworthiness of the issuing company, its credit rating, the time to maturity, the issuance terms, and the ease of selling before maturity.
Choosing corporate bonds based solely on the interest rate is like,
“applying for a job based only on the hourly wage, only to find out the workplace is in Antarctica”
which could lead to an accident.
13. Precaution 4: Pay attention to the time to maturity as well
Generally, the longer the time to maturity for a corporate bond, the longer the time for interest rates and the company’s credit status to change during that period.
Especially after buying a long-term fixed-rate corporate bond,
Market interest rate: “It has risen even further!”
Newly issued bonds: “They have even higher interest rates!”
Your corporate bond: “It remains at the old, low interest rate”
is a possibility.
This is interest rate fluctuation risk.
Therefore,
instead of saying, “It’s a 10-year bond because the interest rate is high!”
you need to consider,
do I really not need to use that capital for 10 years?
you need to think about this.
14. Who is a good match for corporate bonds for individuals?
Corporate bonds for individuals are financial products that are relatively well-suited for
people who prioritize somewhat predictable interest income over large capital gains and have surplus funds they can hold until maturity.
with these types of people.
Conversely,
if you think, “I might use this for a home purchase next year,”
or “I want to be able to cash out the full amount at any time,”
or “I cannot accept any possibility of a loss of principal,”
you need to be cautious with such funds.
Corporate bonds
may look like something between a deposit and a stock, but they are not deposits.
This is likely the most important point.
15. Corporate bonds for individuals in an era of rising long-term interest rates
The rise in long-term interest rates shows two faces to the corporate bond market.
For those who will be purchasing from now on,
Newly issued corporate bonds tend to have higher interest rates and yields
is one of their attractions.
On the other hand, for those who already hold fixed-rate corporate bonds,
there is a possibility that the market price of existing bonds will fall
.
In other words,
Long-term interest rates: “They’re going up!”
New buyers: “Oh!”
Existing bondholders: “I don’t plan on selling midway, so let’s stay calm”
Companies: “Our borrowing costs are going up!”
It is a world where reactions differ completely depending on one’s position.
Conclusion—Corporate bonds are not “products to look at for interest rates” but “products to look at for who you are lending to”
The greatest attraction of corporate bonds for individuals is the ability to lend money to companies through a relatively easy-to-understand mechanism and receive interest.
And in phases where long-term interest rates rise, the interest rates and yields of newly issued corporate bonds also tend to rise, increasing their presence for individual investors.
However, you must not forget.
Corporate bonds are loans to companies.
Therefore, the most important question is
not just
“What is the interest rate?”
“Who are you lending your money to?”
is.
Corporate Bond: “It’s 3% per year!”
Investor: “Oh!”
Corporate Bond: “By the way, regarding the issuing company…”
Investor: “Tell me that first!”
This level of caution is just right.
Retail corporate bonds are “plain but hardworking financial products.” However, it is important to understand that these are investment products with credit risk, interest rate fluctuation risk, and liquidity risk, not principal-guaranteed deposits. The Japan Securities Dealers Association also publishes reference price information for retail corporate bonds, and the target issue information is updated as of October 2026.
Stock: “Let’s aim for a ten-bagger!”
Corporate Bond: “I will calmly pay interest until maturity.”
Deposit: “I can be withdrawn immediately.”
Investor: “Everyone is different, and everyone is good.”
—In a world with interest rates, “plain corporate bonds” are surprisingly leading players.
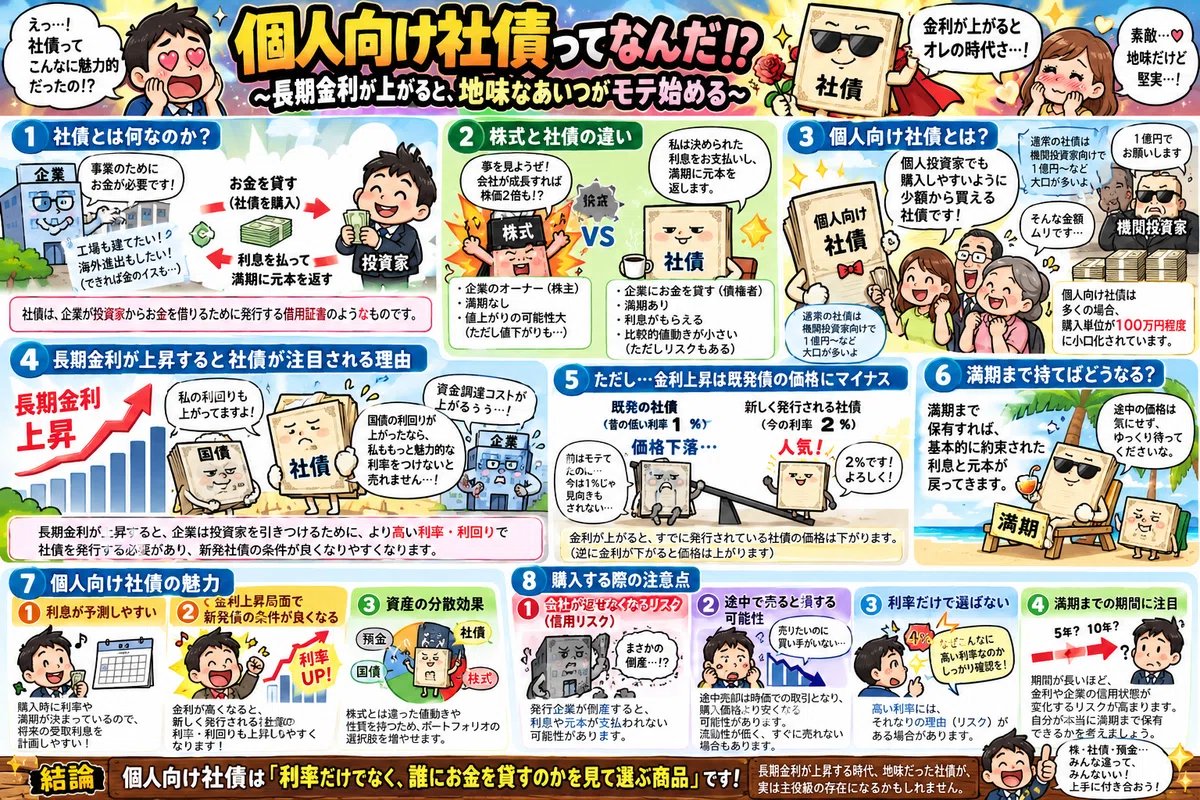
Retail Corporate Bonds: Why These Quiet Investments Get More Attractive When Long-Term Interest Rates Rise
Introduction: Stocks Aren’t the Only Game in Town
When people hear the word “investment,” stocks usually steal the spotlight.
When stock prices soar:
“YES! To the moon!”
When they crash:
“Why did I check my portfolio before breakfast?”
Meanwhile, sitting quietly in the corner is another investment: the corporate bond.
Corporate Bond: “I’ll pay you interest regularly and return your principal at maturity.”
Investor: “Hmm. Not exactly exciting.”
But when interest rates rise, something interesting happens.
Corporate Bond: “My interest rate is a little higher now.”
Investor: “Excuse me?”
Corporate Bond: “Higher yield.”
Investor: “Wait… have you always been this attractive?”
Welcome to the world of retail corporate bonds.
Let’s examine what corporate bonds are, how they are connected to rising long-term interest rates, why they can be attractive to individual investors, and what risks investors should understand before buying them.
1. What Exactly Is a Corporate Bond?
A corporate bond is basically a way for a company to borrow money from investors.
Companies need money for all sorts of reasons.
They may want to build a factory.
They may want to construct a data center.
They may want to develop a new product.
They may want to expand overseas.
Or perhaps the CEO wants a solid-gold office chair.
The shareholders may have a few questions about that last one.
Anyway, companies need capital.
They can borrow money from banks, but they can also raise money directly from investors by issuing corporate bonds.
The basic relationship looks like this:
Investor → Money → Company
Then:
Company → Interest + Principal at Maturity → Investor
In other words, when you buy a corporate bond, you are essentially saying:
“Dear Company, you may use my money for several years.”
And the company replies:
“Thanks! I’ll pay you interest and return the money later.”
It is basically the financial version of lending someone your favorite pen and saying:
“Please give it back.”
Except the pen may be worth ¥1 million.
2. How Are Corporate Bonds Different from Stocks?
This distinction is extremely important.
When you buy shares in a company, you become a shareholder—one of the company’s owners.
When you buy its bonds, you become a creditor—someone who has lent money to the company.
Stocks generally do not have maturity dates.
Corporate bonds usually do.
A bond might say:
“We will repay the principal on December 1, 2031.”
Until then, the investor generally receives interest according to the bond’s terms.
Stocks say:
“If this company becomes huge, your investment might double!”
Bonds say:
“I have an interest payment schedule.”
Stocks: “Dream big!”
Bonds: “Please see page 17 of the prospectus.”
They have very different personalities.
3. What Are Retail Corporate Bonds?
Many corporate bonds are primarily issued to institutional investors such as banks, insurance companies, pension funds, and investment funds.
Retail corporate bonds, however, are designed so that individual investors can purchase them more easily.
They may be issued in smaller denominations than institutional bonds.
Institutional Investor: “I’ll take ¥1 billion.”
Individual Investor: “Could everybody please stop saying ‘billion’ so casually?”
Retail corporate bonds make participation possible on a much smaller scale, although minimum investment amounts and other conditions vary considerably from one bond to another.
4. Why Do Rising Long-Term Interest Rates Matter?
Now we reach the main event.
Corporate bond yields do not exist in isolation.
When companies issue bonds, investors compare their yields with those available from other investments, especially government bonds.
Imagine a world in which government bond yields are extremely low.
A company says:
“Our corporate bond pays 1%.”
Investors might say:
“Not bad.”
But suppose long-term interest rates rise and government bonds begin offering substantially higher yields.
The company returns:
“Our corporate bond still pays 1%!”
Investors:
“Umm… no.”
Why?
Because investors are taking additional credit risk when they lend money to a company.
If relatively safe government bonds offer higher yields, companies generally need to offer more attractive yields to persuade investors to accept corporate credit risk.
Therefore, when market interest rates rise, newly issued corporate bonds tend to face upward pressure on their yields and coupon rates.
Long-Term Interest Rates: “We’re going up!”
Government Bond Yields: “Us too!”
Corporate Bonds: “Apparently we need to offer better terms!”
Companies: “Our financing costs! NOOOOO!”
And that is one reason corporate bonds become more noticeable when interest rates rise.
5. But Rising Rates Aren’t Good News for Every Bondholder
Here comes one of the most important rules in the bond market:
When market interest rates rise, the prices of existing fixed-rate bonds generally fall.
And:
When market interest rates fall, existing bond prices generally rise.
Why?
Imagine you previously bought a bond paying 1%.
Then interest rates rise, and newly issued bonds with similar credit quality begin paying 2%.
New Bond: “2%!”
Old Bond: “1%!”
Investor: “I’ll take the 2% one.”
Old Bond:
“WAIT! COME BACK!”
To make the older 1% bond competitive in the secondary market, its market price generally needs to fall.
That is the basic logic behind the famous relationship:
Interest rates ↑ → Existing bond prices ↓
and
Interest rates ↓ → Existing bond prices ↑
It is one of the great laws of Bond World.
6. What If You Hold the Bond Until Maturity?
This is an essential point.
Suppose you buy a bond for ¥1 million.
Later, because interest rates rise, its market value falls to ¥950,000.
Investor:
“AAAAAH! I LOST ¥50,000!”
Bond:
“Are you selling me today?”
Investor:
“No.”
Bond:
“Then perhaps calm down.”
For a conventional bond, assuming the issuer remains able to meet its obligations and the bond is redeemed according to its terms, an investor who holds it until maturity receives the scheduled redemption amount.
That is very different from selling the bond before maturity.
If you sell early, you generally receive the current market price, which may be higher or lower than the amount you originally paid.
Therefore, one of the most important questions for a corporate bond investor is:
“Am I prepared to hold this bond until maturity?”
7. Attraction No. 1: Predictable Interest Income
One major attraction of conventional fixed-rate corporate bonds is their relative predictability.
The coupon rate and maturity date are generally known when you buy the bond.
That makes it easier to estimate your expected interest income if you intend to hold the bond until maturity.
Ask the stock market:
“What will this stock be worth three years from now?”
Stock Market:
“LOL. Good luck.”
Ask a fixed-rate bond:
“When is your next scheduled interest payment?”
Bond:
“Right here on the calendar.”
For investors who value predictable cash flows, that can be appealing.
8. Attraction No. 2: Rising Rates Can Improve New-Bond Yields
During years of extremely low interest rates, bond investors often had one major complaint:
“Where is the yield?”
But when market interest rates rise, newly issued corporate bonds generally need to offer more competitive yields.
That can make them more attractive to investors who are not necessarily chasing spectacular capital gains but would like to earn meaningful interest income.
The bond market, after a very long nap:
“Good morning. We have yield again.”
For conservative investors, that can be a major change.
9. Attraction No. 3: Bonds Can Add Variety to a Portfolio
Suppose your entire investment portfolio consists of stocks.
Then the stock market crashes.
Stock Market:
“Everybody down!”
Your Portfolio:
“WE’RE ALL GOING TOGETHER!”
Holding different types of assets—such as cash, government bonds, corporate bonds, and stocks—can help diversify a portfolio.
Corporate bonds have different characteristics from stocks because the investor is primarily expecting contractual interest and principal payments rather than ownership-related capital appreciation.
However, diversification does not mean that corporate bonds are risk-free.
And that brings us to the important part.
10. Warning No. 1: The Company Might Not Be Able to Repay You
The biggest danger with corporate bonds is credit risk.
Remember:
Buying a corporate bond means lending money to a company.
If the company experiences serious financial trouble, it may fail to pay interest or repay the principal as promised.
Company:
“About that money we owe you…”
Investor:
“Why did you start the sentence like that?”
This is why a corporate bond is fundamentally different from a bank deposit.
A bond is an investment product, not simply money sitting in a savings account.
Before purchasing one, investors should examine factors such as:
the issuer’s financial condition, business prospects, debt levels, credit rating, and the specific terms of the bond.
And be particularly careful when you see an unusually high yield.
Investor:
“WOW! This bond pays much more than everything else!”
Before celebrating, ask:
“Why does this company need to pay such a high yield to attract investors?”
Higher potential returns often come with higher risk.
In finance, there is rarely a magical free lunch.
And if somebody is offering an enormous free lunch, check whether the restaurant is on fire.
11. Warning No. 2: Selling Before Maturity Can Hurt
Imagine buying a five-year corporate bond.
One year later:
“Oh no! I need this money!”
You decide to sell.
Unfortunately, there is no guarantee that you can sell the bond for the price you originally paid.
If market interest rates have risen, your existing bond may be less attractive than newly issued bonds, causing its market price to fall.
There is also liquidity risk.
Some corporate bonds do not trade nearly as actively as major stocks or government securities.
That means you may have difficulty finding a buyer at the price you want.
Therefore, investing money that you may suddenly need next year into a long-term corporate bond deserves careful thought.
Emergency fund:
“Please leave me out of this.”
12. Warning No. 3: Never Choose a Bond Based Only on Its Coupon Rate
Imagine three corporate bonds:
Company A: 1.5%
Company B: 2.0%
Company C: 4.0%
Investor:
“COMPANY C! TAKE MY MONEY!”
Not so fast.
The important question is:
Why does Company C need to offer 4%?
Perhaps the company is perfectly healthy and market conditions explain the difference.
But perhaps investors demand a higher return because they perceive greater risk.
When comparing bonds, investors should consider not only the coupon rate or yield but also:
-
the issuer’s creditworthiness,
-
credit ratings,
-
maturity,
-
redemption terms,
-
liquidity,
-
special bond conditions,
-
and the overall financial health of the issuer.
Choosing a bond purely because it has the highest interest rate is like choosing a job purely because it has the highest salary—
and discovering afterward that the office is in Antarctica.
Salary: Excellent.
Commute: Penguins.
13. Warning No. 4: Pay Attention to Maturity
Suppose you buy a long-term fixed-rate corporate bond.
Then market interest rates continue rising.
New Bonds:
“Higher yields!”
Your Old Bond:
“I’m still paying the rate we agreed on years ago.”
You:
“Hmm.”
The longer the maturity, the longer your money may be committed and the greater the potential sensitivity of the bond’s market price to changes in interest rates.
Meanwhile, the company’s financial condition can also change over time.
Therefore, investors should ask themselves:
“Can I really leave this money invested until maturity?”
A high coupon rate alone should not decide the answer.
14. Who Might Find Retail Corporate Bonds Attractive?
Retail corporate bonds may appeal particularly to investors who:
want relatively predictable interest income,
are willing to accept corporate credit risk,
have money they can potentially leave invested until maturity,
and do not necessarily need the dramatic upside potential of stocks.
But they may be less suitable for money that must remain immediately available.
For example:
“I’m buying a house next year.”
“I may need all of this money for emergencies.”
“I absolutely cannot tolerate any possibility of loss.”
In those cases, corporate bonds require particular caution.
The key idea is simple:
A corporate bond may sometimes feel like something between a bank deposit and a stock—but it is not a bank deposit.
15. Corporate Bonds in a World of Rising Long-Term Interest Rates
Rising long-term interest rates have two very different effects on the corporate bond market.
For investors considering newly issued bonds, higher market rates can mean more attractive yields.
But for investors already holding existing fixed-rate bonds, higher rates can reduce the bonds’ market value.
So when long-term rates rise:
Long-Term Rates:
“UP WE GO!”
New Bond Buyer:
“Ooh, interesting.”
Existing Bondholder:
“I’m holding to maturity. Everybody remain calm.”
Company Treasurer:
“WHY IS OUR BORROWING COST GOING UP?!”
Same interest-rate movement.
Completely different reactions.
Welcome to finance.
Conclusion: Don’t Just Ask “What’s the Interest Rate?” Ask “Who Am I Lending Money To?”
The attraction of retail corporate bonds is relatively straightforward.
Investors lend money to companies, receive interest according to the bond’s terms, and expect repayment at maturity.
When long-term interest rates rise, newly issued corporate bonds may offer more attractive yields, increasing their appeal to individual investors.
But there is one thing investors should never forget:
A corporate bond is a loan to a company.
Therefore, the most important question is not simply:
“What’s the coupon rate?”
It is also:
“Who am I lending my money to?”
Bond:
“I pay 3%!”
Investor:
“Nice!”
Bond:
“And the company issuing me is…”
Investor:
“YES. THAT PART. PLEASE TELL ME THAT PART FIRST.”
Retail corporate bonds can be useful investments for people seeking interest income and portfolio diversification.
But they still involve credit risk, interest-rate risk, price risk, and liquidity risk.
Stocks may shout:
“Let’s find the next ten-bagger!”
Corporate bonds quietly reply:
“I’ll just sit here and make my scheduled payments.”
Cash says:
“I’m available whenever you need me.”
Investor:
“You know what? Maybe there’s room for all of you.”
And that is the key lesson:
In a world where interest rates have returned, the quiet corporate bond may suddenly have a much bigger role to play.