
WisdomTree has launched two new autocallable ETFs onto Xetra and Borsa Italiana, marking its first foray into the defined outcome market.
The WisdomTree Defined Return Autocallable EUR Active UCITS ETF (DRTN) and WisdomTree Defensive Defined Return Autocallable EUR Active UCITS ETF (DRTD) each have a total expense ratio of 0.65%.
They will aim to achieve predictable equity investment returns through actively-managed allocations to autocallables on large-cap liquid indices such as the EUROSTOXX 50.
Autocallables are a type of structured investment which are linked to indices. They typically pay investors a coupon and mature early, if the index it is linked to reaches a certain trigger level on set dates.
See also: HANetf launches world’s first euro-hedged bitcoin ETC
The launch comes shortly after WisdomTree’s acquisition of Atlantic House, which launched the first autocallable UCITS fund in 2013 and currently manages more than $4bn across a range of autocallable mandates.
Alexis Marinof, CEO, Europe at WisdomTree, said: “Options-based ETFs are one of the fastest-growing segments of asset and wealth management as investors seek greater certainty around outcomes.
“This structural demand is creating a significant opportunity for differentiated and actively managed ETFs in Europe as investors increasingly look for alternatives to traditional structured product certificates.
“Our ambition is clear: leveraging the outcome and derivatives expertise gained through the Atlantic House acquisition, we intend to launch 15-20 strategies globally over the next 18 months and become a leader in the category.”
See also: Sprott and HANetf launch rare earths ex-China ETF
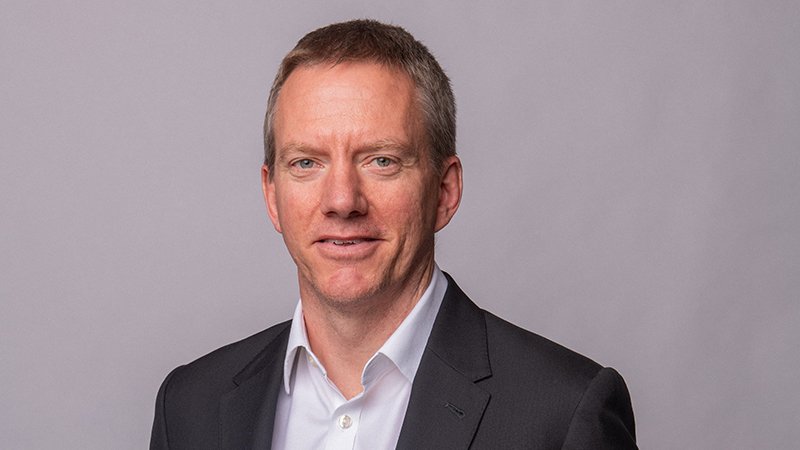
Tom May (pictured), global CIO, outcome and derivative strategies at WisdomTree, added: “Active management and derivatives expertise is particularly important in defined return strategies because market conditions do not remain static.
“While investors have traditionally accessed these types of outcomes through structured product certificates, our diversified portfolio approach is designed to improve the consistency of outcomes over time.
“By actively adjusting underlying exposures, barrier levels, protection thresholds, term, and overall payoff design, the portfolio management team seeks to maximise the likelihood of achieving the desired returns compared to a purely static or index-based approach.”